
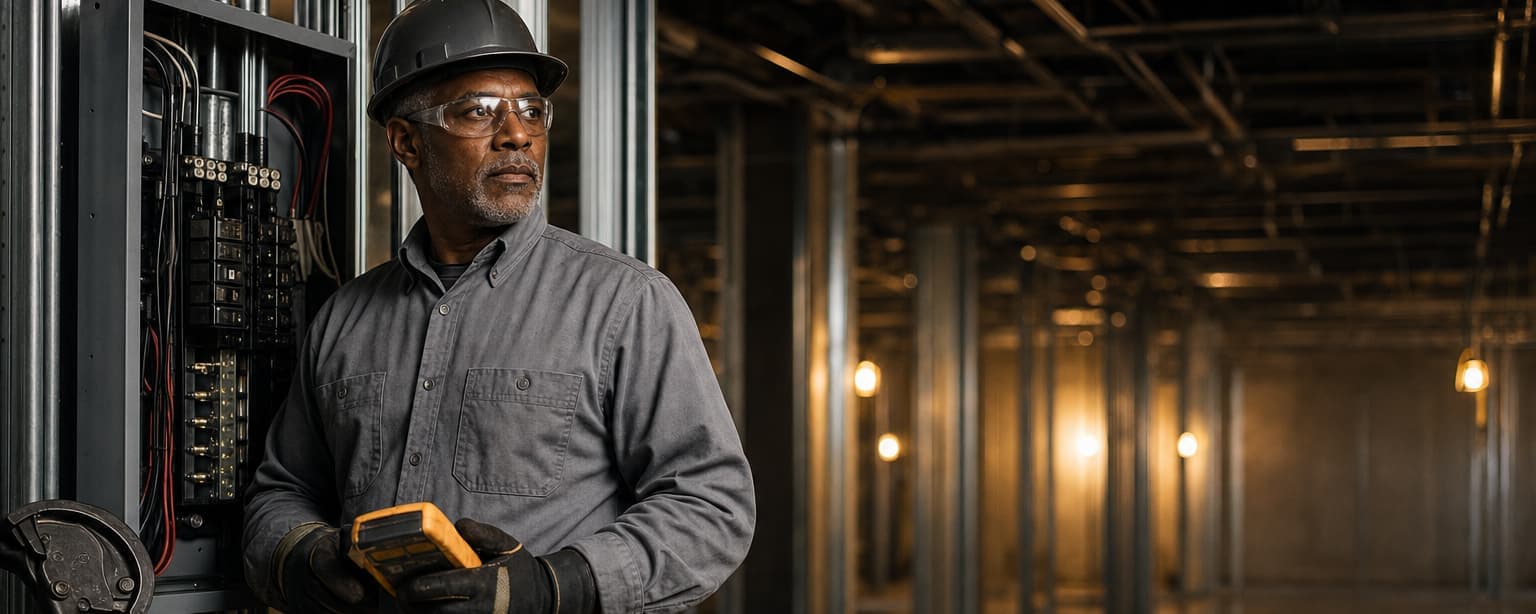
The fire happens years after the job closes.
Commercial insurance for electricians and electrical contractors, written around completed operations, arc flash and the voltage you actually work, not around a package.
Tell us the situation.
One licensed human replies the same business day — not five agents, not an auto-responder. If the policy you have is already the right one, we will tell you.
We use this to quote and service your insurance, and we do not sell it or pass it to lead networks. Privacy policy.
Send us what you have. We’ll tell you if it’s right.
Your current policy paperwork, a renewal notice, or nothing at all. A licensed agent reads it and replies the same business day.
What electrical contracting businesses actually need.
General liability
Third-party bodily injury and property damage. It is the line nearly every contract names by default.
Without it — A fault in finished work starts a fire in somebody else’s building, and the claim names the contractor who signed the work off.
Workers compensation
Required in almost every state the moment you have employees. Priced on payroll and class code, which is why the class code is worth arguing about.
Without it — Arc flash and electrocution are severity injuries rather than frequency ones: a single incident is a burn unit, not a week off.
Contractors errors & omissions
Covers faulty workmanship and professional mistakes: the cost of the work itself being wrong, which general liability excludes by design.
Without it — Specifying or designing a system that fails to perform is a professional claim, and design-build work puts it in play on almost every job.
Commercial auto
Vehicles the business owns and the people who drive them for work.
Without it — A van full of material on the way to a call is a work trip, and a personal auto insurer will decline it once they learn that.
Inland marine & equipment
Tools, equipment and property in transit. It picks up exactly where commercial property stops, which is the moment the item leaves the building.
Without it — Test equipment, benders and reels walk off sites, and property coverage stops at the shop door.
Umbrella & excess liability
Extra limit stacked above general liability, auto and employers liability. Usually the cheapest million dollars on the policy.
Without it — Commercial contracts require limits above primary, and a fire loss exhausts a primary limit without argument.
Contractors pollution liability
Bodily injury, property damage and clean-up caused by a pollutant your work released: chemical drift, run-off, fuel spills. The standard general liability form excludes all of it.
Without it — Oil-filled gear, PCB-era transformers and burned insulation are a clean-up bill, and the pollution exclusion reaches all three.
Surety bonds
License, bid and performance bonds. A bond guarantees you will finish the job. It protects the other party, not you, which is the part most people get wrong.
Without it — License and permit bonds are a condition of holding the license in most jurisdictions, and contract bonds decide which jobs can be bid.
Key person & buy-sell funding
If an owner or an irreplaceable employee dies, this is the money that keeps the business running and funds the buy-sell agreement so the surviving owners can buy out the estate instead of ending up in business with it.
Without it — Where one license holder qualifies the company, their death is a licensing emergency before it is anything else.
Joe Gorman
Co-Founder | President of Commercial Lines
Came up in construction, on site and in the office, then moved into sales. Went out on a limb to become Boring’s first dedicated salesperson when the agency had no sales team at all, and now leads it. Landscaping is the class he writes most: grounds maintenance, tree work, irrigation and the spray operations that push an account out of preferred appetite.
Five endorsements, and a certificate is none of them.
A certificate is evidence a policy existed the day it was printed — it says so on its own face. The coverage a contract is really asking for lives on the policy as named endorsements, and this is the list they come from.
- Additional insured — ongoing operationsCG 20 10Covers the general contractor for claims arising from your work while the job is in progress.Without it: They fund their own defense on a claim your work caused, then look to you for it.
- Additional insured — completed operationsCG 20 37Extends that coverage to claims arising after your work is finished.Without it: The claim arrives years later, when the policy that should have carried it has renewed several times. Cheaper policies often exclude this or do not offer it.
- Primary and non-contributoryCG 20 01Puts your policy first and stops your insurer demanding a contribution from theirs.Without it: Two insurers argue about who pays while the defense waits.
- Waiver of subrogationCG 24 04Stops your insurer recovering from the party you agreed in writing to protect.Without it: Your insurer pays, then sues your customer, which ends the relationship.
- Per-project aggregateCG 25 03Gives each job its own general aggregate instead of sharing one across the year.Without it: Another project’s claims quietly spend the limit that was meant to cover this one.
Tract, condominium and apartment work is the exception that undoes all five — an exclusion for multi-unit residential removes the coverage before any endorsement can apply. What national homebuilders require covers that in full — D.R. Horton, Pulte Group, Blackrock Homes and the rest of the national builders set the strictest terms a sub will see, and they do not negotiate them.
Contracts ask for more than these five. Every contract insurance requirement, explained, or paste your exhibit into the Contract Insurance Decoder to see the endorsement behind each clause.
How high do you work?
Third floor and above is a different account. The exposure is not only the fall — it is what gets dropped, who is underneath, and how far a tool travels before it lands. Carriers ask for a height limit and many stop at two or three stories, so work you take on because it was offered can quietly put a renewal into a market you were not in last year. Tell us the tallest job you do, not the usual one.
Residential or commercial?
Underwriters treat these as separate trades even when the work is identical. Residential carries construction-defect exposure that follows the job for years and a homeowner who sues; commercial carries bigger limits, tighter contracts and a general contractor who enforces them. A book that is mostly one prices very differently from a book that is evenly split, and the mix is usually the second question on the application.
An electrical contractor in California that installs large-scale charging station hubs was non-renewed on its commercial auto because the business had grown too fast for the carrier, and came to us 24 hours before the policy lapsed. California commercial auto is a hard market on a good day, and a fleet that has outgrown its file is exactly what the standard carriers decline.
We had the fleet covered the next business day. No lapse, no trucks parked, and no time lost at the job site while a general contractor waited on a certificate. Rapid growth reads as risk to the carrier that wrote the small version of the business. To a market that writes the size you are now, it is just the application.
What the insurance company will ask about your electrical contracting business
We read the applications the markets use for businesses in this field and pulled out what they actually ask. Have these answers ready and a quote takes a day instead of a week, because nobody has to come back to you for the missing piece.
About the business
- Your company name, address, phone number, and main contact
- When did you start this business?
- How many people do you employ total?
- What professional associations or unions are you part of?
How you operate
- What types of sprinkler systems do you design and install (new construction, retrofits, repairs)?
- What percentage of your work is new systems versus fixing or upgrading existing ones?
- What types of piping do you use (steel, CPVC, copper, or other)?
- Do you do any work besides fire sprinklers, like plumbing, HVAC, excavation, or other trades?
- Which trades do you hire as subcontractors?
Safety and controls
- What type of testing do you do on new CPVC systems (water only, air only, or both)?
- How long does CPVC pipe take to cure, and do you adjust cure times based on temperature and humidity?
- Do you test water supply to make sure there's enough for the systems you design?
- Do you require all systems to be tested before you sign off, whether new, retrofit, or repair?
- Do you protect building surfaces and property during retrofit and repair work, and do you document this?
Your history
- How many years have you designed sprinkler systems?
- Do you design all systems in line with NFPA 13, NFPA 13-R, and NFPA 13-D standards?
- Do you do your own system design work or use outside designers?
- Have you had any professional liability claims from systems you designed? If yes, explain
- In the last five years, have you been cited or prosecuted for releasing substances like chemicals into sewers, water, air, or land?
Money and people
- What is your total gross sales?
- How much of your sales come from wrap-up insurance projects, and how much excluding those?
- What percentage of your revenue comes from each type of building (institutional, commercial, residential, manufacturing)?
- What is your federal tax ID number?
Have these ready
- Your CPVC training program name and certification credentials
- A list of all subcontractors and their certificates of insurance
- Copy of any alarm monitoring agreement if you provide that service
- Documentation showing water supply testing records for systems you've designed
- Your loss runs (claims history from your current insurer for the last five years)
You answer what you can; a licensed agent fills the rest with you.
What our electrical contracting clients ask us.
Why do carriers care so much about completed operations for electricians?
Because the loss shows up long after the invoice is paid. A loose connection or an undersized conductor can sit behind a wall for years, heat slowly, and then start a fire in a building that has changed hands twice since. That is a completed operations claim, and it is the reason a general contractor asks electricians for additional insured wording covering completed operations, not just ongoing. If the endorsement was not on the policy when the work was done, it does not help you when the claim arrives.
Does the voltage I work change what I can buy?
Yes, and it is usually the second question on the application. Residential and light commercial service work sits in a broad market. High voltage, line work, substation and utility work narrows it sharply, and some carriers stop entirely at a stated threshold. Solar, EV charging and battery storage are treated as their own questions now rather than as ordinary electrical, because the loss history on them is short and the fire exposure is not. State what you actually do — understating it is how a claim gets contested after the fact.
What do general contractors ask electrical subs for?
The full stack, and more of it than most trades: additional insured for ongoing and completed operations, primary and non-contributory wording, a waiver of subrogation, and often a per-project aggregate so one bad job does not exhaust the limit for every other. On larger commercial work an umbrella somewhere between one and five million is normal. Send the subcontract before you sign it and we will tell you which of those you already have.
I was non-renewed after a fire claim. Is that the end of it?
No, though it changes where the account goes. A fire loss on an electrical account is exactly the kind of history the standard market declines and the excess and surplus market prices. What matters is how the submission is put together — the cause, what changed afterwards, and whether the work mix that produced the loss is still the work mix. An account presented with the loss explained places very differently from the same account presented with the loss buried.
How is electrical contractor insurance priced?
Mainly on payroll and class code, then on the split between residential, commercial and industrial work, and then on loss history. The most common reason an electrician overpays is misclassification — service work rated as new construction, or all payroll landed in the highest available code. It is worth checking before you shop, because the audit at the end of the year is where it gets settled either way.
Do I need workers comp to get a Florida electrical contractor license?
You need workers comp or a state exemption certificate. Florida Statutes section 489.515 asks an applicant for an electrical contractor certification to swear to both workers comp or an exemption and liability and property damage insurance. A construction business with even one employee must carry workers comp in Florida, and only up to three owners with 10% or more each can exempt themselves.
How much is workers comp for a small electrical contractor?
It follows payroll, so ask with your payroll figure in hand. On our calls in 2026 two markets quoted a small Florida residential and commercial electrical shop at about $6,300 and $6,400 a year, and the questions that moved the rate were the voltage worked, ladder height, trenching and whether any work was subcontracted. Ask for the down payment as well as the annual premium.
What does a electrical contracting insurance application ask for?
The applications for electrical contracting businesses ask about 4 things above all: your company name, address, phone number, and main contact; what types of sprinkler systems do you design and install (new construction, retrofits, repairs); what type of testing do you do on new cpvc systems (water only, air only, or both); how many years have you designed sprinkler systems. Have your cpvc training program name and certification credentials and a list of all subcontractors and their certificates of insurance ready and a quote takes a day instead of a week.
Guides on electrical contracting.
- Do insurance companies look at your website?Underwriters compare your website with your application, and a mismatch costs a quote or a policy. What they read, what a misstatement can do to a claim, and how to send a submission that matches the site.
- Florida workers comp for contractorsFlorida’s one-employee rule for construction, the officer exemption and its limits, what the licensing boards ask for, and what working uncovered costs, each quoted from the Florida Statutes.
Commercial insurance is 96% of what we do — it is not a department here, it is the whole business. Not ready to talk? The guides answer the questions this page raises in more depth. Already insured with us and need a certificate or a policy change? Ask the service team rather than starting a quote — it is faster and it goes to the people whose job it is. We also write home and auto, which is usually cheaper alongside the business policy than apart from it.