
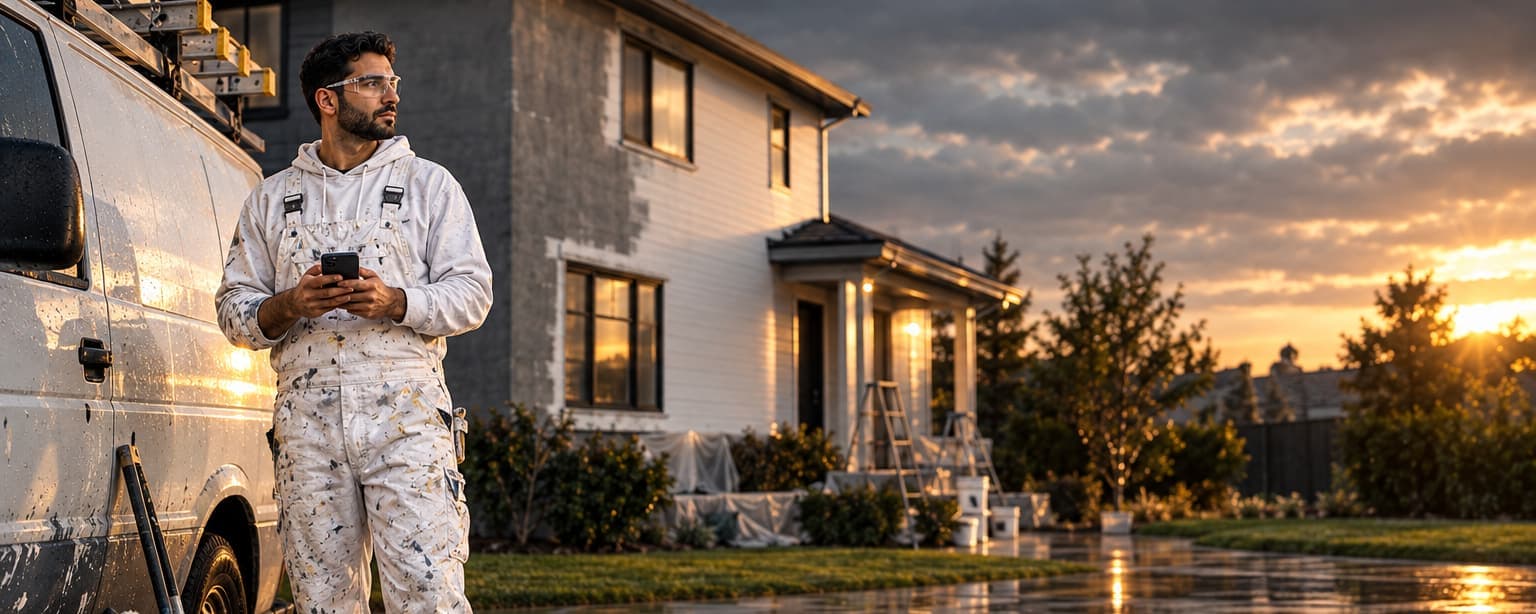
Do insurance companies look at my business website?
Yes. The standard commercial insurance application asks for your website address, and underwriters read the site to check the operations you described. On our calls in 2026 a painting contractor’s workers comp was cancelled after binding because his website advertised general contracting, and a second carrier declined him for the same reason. If your site lists work you do not do, fix it or explain it in the submission before the underwriter finds it.
Tell us the situation.
One licensed human replies the same business day — not five agents, not an auto-responder. If the policy you have is already the right one, we will tell you.
We use this to quote and service your insurance, and we do not sell it or pass it to lead networks. Privacy policy.
Joe Gorman
Co-Founder | President of Commercial Lines
Came up in construction, on site and in the office, then moved into sales. Went out on a limb to become Boring’s first dedicated salesperson when the agency had no sales team at all, and now leads it. Landscaping is the class he writes most: grounds maintenance, tree work, irrigation and the spray operations that push an account out of preferred appetite.
Send us what you have. We’ll tell you if it’s right.
Your current policy paperwork, a renewal notice, or nothing at all. A licensed agent reads it and replies the same business day.
The detail
The ACORD 125 commercial insurance application, the form most carriers start from, has a "WEBSITE ADDRESS" field for the applicant.
ACORD 125 Commercial Insurance Application (2024/11), as published by Merchants Insurance Group
The same application asks for the nature of the business and a description of primary operations, and asks whether the applicant has other business ventures for which coverage is not requested.
ACORD 125 Commercial Insurance Application (2024/11), as published by Merchants Insurance Group
In Florida, a statement in an application is a representation, and a misrepresentation, omission or incorrect statement may prevent recovery under the policy if it is fraudulent or material to the acceptance of the risk, or if the insurer in good faith would not have issued the policy, or would not have issued it at the same premium rate, had it known the true facts.
Florida Statutes section 627.409, Representations in applications
Between August and October 2026, one carrier cancelled a painting contractor’s newly bound workers comp policy after its underwriter saw general contracting on his website, and a second carrier declined to write him for the same reason, leaving one market at roughly $9,000 for New Jersey alone.
Boring Insurance call records, calls from Aug to Oct 2026 (clients and carriers unnamed)
In the same period an underwriter quoting a New York commercial cleaning company asked about hood cleaning, marble floor restoration and hospital and surgery center cleaning because the company’s website listed them. The owner confirmed it did none of them.
Boring Insurance call records, calls from Aug to Oct 2026 (clients and carriers unnamed)
What this means for you
- Read your own site the way an underwriter would. Every service listed is a service you may be rated for. A painter whose site says "general contracting" will be classed as a general contractor, and a cleaner whose site says "hospital cleaning" will be asked about medical waste.
- Take down what you do not do, or say why it is there. If a service is old, rare or always subcontracted, write that in the submission with the percentage of revenue, before the question is asked.
- Expect the class code to follow the site. Workers comp is priced by the class of work, and the cheaper class only holds if the work matches it. A misclassified policy is corrected at the audit, usually with a bill.
- An honest application protects the claim. A misstatement that would have changed the price or the decision can let the carrier refuse a claim in many states, Florida among them. A policy that costs more and pays is worth more than one that costs less and does not.
Go deeper on any of these
Related questions
- Can an insurer cancel a policy I already paid for because of my website?
It can, especially early in the policy. On our calls a painting contractor’s workers comp was bound with payment taken and then cancelled by the carrier when its underwriter read the website, and the next markets either declined or priced the account as general contracting.
- Does it matter if the work on my site is subcontracted?
Yes, and say so. A general contractor that subcontracts everything is still rated for the work it takes on, and the underwriter will want the subcontractors’ certificates. Put the split in the submission rather than leaving the site to speak for you.
- Subcontractor requirements in a liability policy
- Will they look at reviews and social media too?
Underwriters read whatever is public about an applicant, and a review describing work you did not declare raises the same question as a website. Keep the application consistent with how the business presents itself.
- What happens at the workers comp audit if the class was wrong?
The auditor reclassifies the payroll to the work actually done and bills the difference for the whole year. That is usually larger than the saving the wrong class looked like at the start.
- How the workers comp audit works
Need this handled?
Reading about it and having it handled are different jobs, and the second one is ours. We place the accounts other brokers decline — claims history, a cancellation, an unusual operation, a business nobody wants to underwrite twice — and we will tell you when the policy you already have is the right one. Tell us the situation and a licensed human replies the same business day.
Written by the licensed brokers at Boring Insurance. Last updated 2026-10-05. See all guides.