
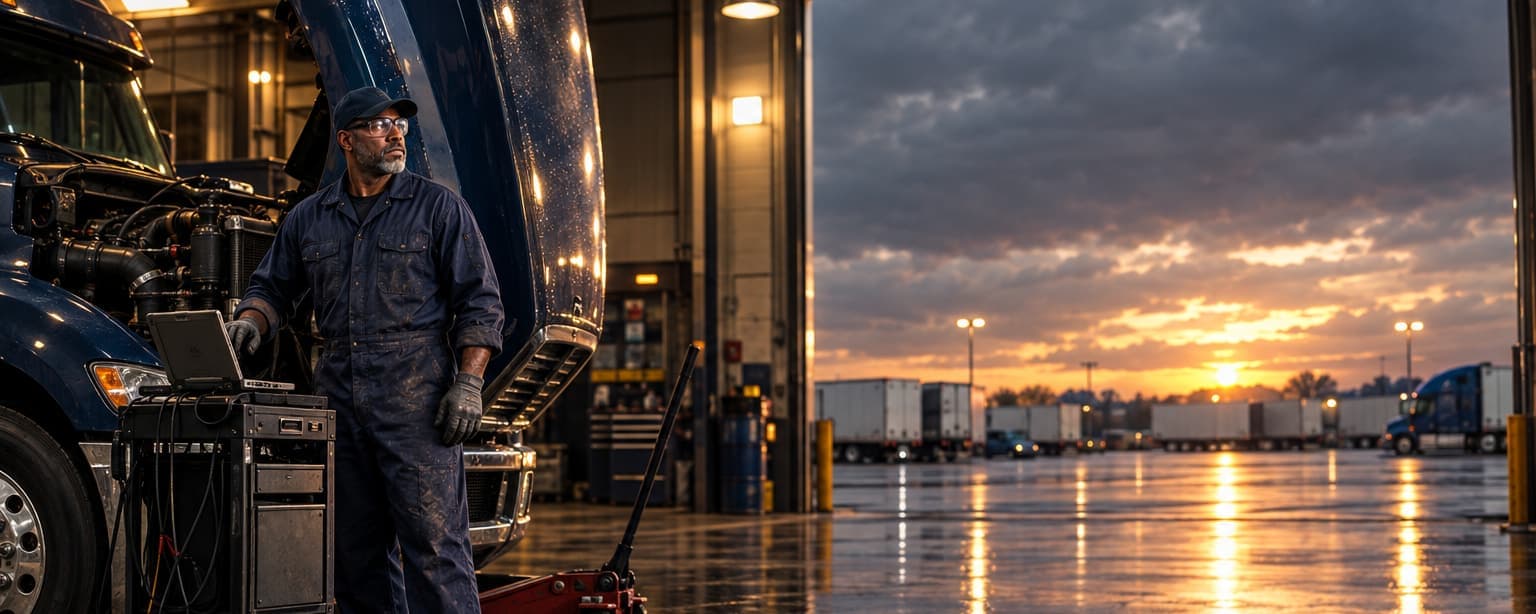
One tractor in your bay can be worth more than your whole garagekeepers limit.
We insure heavy truck and diesel repair shops with general liability that covers work on semi trucks, garagekeepers limits sized to Class 8 tractors and loaded trailers, and the road tests and tows a truck shop runs every day.
Tell us the situation.
One licensed human replies the same business day — not five agents, not an auto-responder. If the policy you have is already the right one, we will tell you.
We use this to quote and service your insurance, and we do not sell it or pass it to lead networks. Privacy policy.
Send us what you have. We’ll tell you if it’s right.
Your current policy paperwork, a renewal notice, or nothing at all. A licensed agent reads it and replies the same business day.
What heavy truck and diesel repair businesses actually need.
General liability
Third-party bodily injury and property damage. It is the line nearly every contract names by default.
Without it — Written to include heavy truck work. Many mechanic programs are built around passenger cars and exclude or limit Class 7 and 8 trucks, which is the gap this page exists for.
Garagekeepers
Customer vehicles in your care, custody and control. Every repair shop and dealership has the exposure and most standard policies exclude it.
Without it — Tractors and trailers in your bays and yard. Set the per-location limit for a full yard of heavy equipment and check any per-vehicle maximum against your most valuable unit.
Commercial auto
Vehicles the business owns and the people who drive them for work.
Without it — Service trucks, the wrecker if you have one, and road tests. Trucks you drive on a customer’s behalf need auto coverage that names that exposure.
Motor truck cargo
The freight itself while you are hauling it. Separate from the liability on the truck.
Without it — On-hook coverage if you tow disabled trucks into the shop. The towed tractor is not covered by your liability policy.
Umbrella & excess liability
Extra limit stacked above general liability, auto and employers liability. Usually the cheapest million dollars on the policy.
Without it — Fleet customers commonly require limits above $1,000,000, and a heavy truck crash exhausts primary limits quickly.
Workers compensation
Required in almost every state the moment you have employees. Priced on payroll and class code, which is why the class code is worth arguing about.
Without it — Heavy components, tire work on truck wheels and work under raised cabs. Severity is higher than passenger car repair.
Inland marine & equipment
Tools, equipment and property in transit. It picks up exactly where commercial property stops, which is the moment the item leaves the building.
Without it — Diagnostic software and laptops, heavy jacks, and technician-owned tools, which are often worth more than the shop’s own.
Commercial property
Buildings and contents, valued at what it costs to rebuild today rather than what you paid.
Without it — Tall bays, heavy lifts and a parts inventory that is expensive and slow to replace.
The claims we actually see.
Ordered by how often we see them, not by how dramatic they are. Each one names the coverage that answers it — and the policy people wrongly assume already does.
Most common
A customer’s tractor is damaged in the bay or the yard
Covered by Garagekeepers, with a per-auto limit set for heavy trucks
Garagekeepers limits are set per location, and many forms or programs cap what they pay for any one vehicle. A limit built for pickups does not cover a late-model tractor.
Rare, catastrophic
A brake or steering repair fails and the truck crashes on the highway
Covered by Completed operations under general or garage liability
Many mechanic general liability programs exclude or limit heavy truck work. A crash involving an 80,000-pound truck is a severity claim, and the limit and the umbrella have to be sized for it.
Less common, severe
A technician road-testing a customer truck causes a crash
Covered by Garage liability or commercial auto that covers customer vehicles you operate
The truck owner’s policy may not answer for your employee, and general liability excludes autos. Road tests need auto liability written for the vehicles in your care.
Less common, severe
A loaded trailer in your yard is damaged or its cargo is stolen
Covered by Garagekeepers for the trailer; the cargo is a separate question
Garagekeepers covers the vehicle, not the freight inside it. If carriers leave loaded trailers with you, find out who insures the load while it is on your lot.
Joe Gorman
Co-Founder | President of Commercial Lines
Has placed hundreds of auto service businesses: repair shops, mobile mechanics, heavy truck garages and the roadside operators most carriers will not look at. He knows which markets still take a garage risk and what garagekeepers limit a full lot actually needs. A mobile operation described the wrong way gets declined on sight, so he describes it the right way.
What the insurance company will ask about your heavy truck and diesel repair business
We read 3 applications the markets use for this kind of business and pulled out what they actually ask. Have these answers ready and a quote takes a day instead of a week, because nobody has to come back to you for the missing piece.
About the business
- What types of auto repair work do you do most often (like oil changes, body work, painting, tire service)
- Do you also sell new or used vehicles, and if so what percentage of your business is sales versus repairs
- How many years have you been doing this type of work
- Do you have a dealer's license, and if so in which states
How you operate
- How many employees do you have working on site
- Do you ever drive customer vehicles to pick them up or deliver them, and how many times per week
- Do you perform any work at customer locations or off-site
- Do you store vehicles on your property overnight after business hours
- Do you ever lease, rent, or loan vehicles to customers
Safety and controls
- If you do painting, do you have a separate spray booth with proper ventilation and explosion-proof lighting
- Do you store paints and solvents in a fire-resistant cabinet outside the paint booth
- Do you have fire extinguishers that are serviced and charged on site
- Are car keys stored in a secure location that only authorized people can access
- Do you leave keys in vehicles
Your history
- What is your claims history from the last three years
- Have you ever had an insurance policy cancelled, declined, or not renewed
- What insurance do you currently have or did you have before
Money and people
- What were your total annual receipts in the last year, broken down by repairs, parts sales, vehicle sales, and any other income sources
- Do you own or operate any other businesses besides this repair shop
Have these ready
- Your last three years of claims history from your current or previous insurer, called loss runs
- A copy of your dealer's license if you have one
- Documentation of any specialized training or certifications you hold related to auto repair
You answer what you can; a licensed agent fills the rest with you.
What our heavy truck and diesel repair clients ask us.
Does a standard mechanic’s general liability policy cover work on semi trucks?
Often not, and it is worth checking before the next job. Many general liability programs written for repair shops are built around passenger cars and light trucks and exclude or sharply limit work on heavy trucks. We place general liability with a specialty market whose program includes heavy truck work, so a brake job on a tractor is covered the same way as one on a pickup.
How much garagekeepers do I need for a truck shop?
Enough for the most valuable full yard you have had, not the average day. Add up the tractors and trailers that are on the property at a busy moment and set the per-location limit there. Then check the per-vehicle cap, because many garagekeepers forms pay no more than a set amount for any one vehicle whatever the location limit says. One truck shop we insure carries $1,000,000 per location with a $300,000 cap per vehicle. A truck shop that also stores trucks for fleets between jobs has a larger and longer exposure than the bays alone suggest.
Who covers my mechanic road-testing a customer’s truck?
Your policy, in most cases, and it has to be written for it. The truck owner’s commercial auto policy may treat your employee as an insured, but many auto policies limit or exclude coverage for people in the business of repairing vehicles, and general liability excludes any auto operated by your business. A garage liability form, or commercial auto with coverage for vehicles in your care, is how road tests are insured.
What if a fleet leaves a loaded trailer at my shop?
The trailer is a vehicle in your care, so garagekeepers can cover physical damage to it. The freight is not a vehicle and is outside garagekeepers. Most of the time the motor carrier’s cargo policy still covers the load, but cargo policies often restrict unattended vehicles and storage locations, so the question is worth putting to the fleet before a trailer is dropped for a week.
Is heavy truck repair hard to insure?
It is a narrower market than passenger car repair, and that is the main difficulty. Fewer carriers want the severity of heavy truck completed operations, so a shop described as general auto repair gets either a policy that excludes its real work or a declination. Described accurately, with the split between shop work and road calls, the technicians’ experience and the size of the yard, it places. The heavy truck and trailer repair shops we insure are written on a specialty garage program through a wholesaler, with $1,000,000 per occurrence liability and garagekeepers from $250,000 to $1,000,000 per location.
What does a heavy truck and diesel repair insurance application ask for?
The applications for heavy truck and diesel repair businesses ask about 4 things above all: what types of auto repair work do you do most often (like oil changes, body work, painting, tire service); how many employees do you have working on site; if you do painting, do you have a separate spray booth with proper ventilation and explosion-proof lighting; what is your claims history from the last three years. Have your last three years of claims history from your current or previous insurer, called loss runs and a copy of your dealer's license if you have one ready and a quote takes a day instead of a week.
Commercial insurance is 96% of what we do — it is not a department here, it is the whole business. Not ready to talk? The guides answer the questions this page raises in more depth. Already insured with us and need a certificate or a policy change? Ask the service team rather than starting a quote — it is faster and it goes to the people whose job it is. We also write home and auto, which is usually cheaper alongside the business policy than apart from it.
Handed a lease, a vendor packet or a client contract with insurance requirements? Paste it into the COI Requirements Decoder to see what each one means for your business, or read what the requirements mean.