
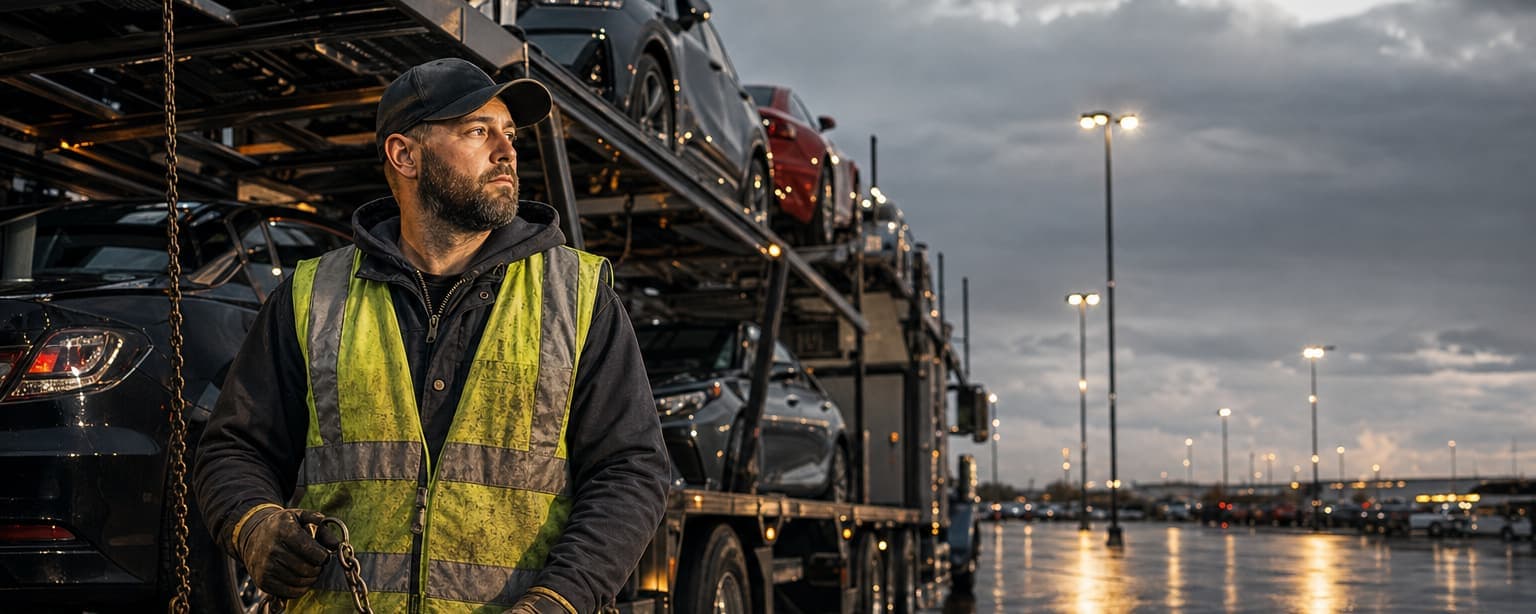
A full load of cars is worth more than most cargo limits.
We write car haulers and auto transporters with cargo limits taken from the value actually on the trailer, rather than from a general freight default.
Tell us the situation.
One licensed human replies the same business day — not five agents, not an auto-responder. If the policy you have is already the right one, we will tell you.
We use this to quote and service your insurance, and we do not sell it or pass it to lead networks. Privacy policy.
Send us what you have. We’ll tell you if it’s right.
Your current policy paperwork, a renewal notice, or nothing at all. A licensed agent reads it and replies the same business day.
What auto hauling businesses actually need.
Motor truck cargo
The freight itself while you are hauling it. Separate from the liability on the truck.
Without it — A general freight cargo limit does not come close to a loaded stinger, and the shortfall is owed by you.
Commercial auto
Vehicles the business owns and the people who drive them for work.
Without it — Primary liability and the filing that keeps the authority active.
Auto physical damage
Damage to your own tractor and trailer. Primary liability pays for what you do to everyone else and nothing for your equipment, so without this a rollover you caused leaves you paying off a truck you can no longer run.
Without it — The rig itself is specialized, expensive and slow to replace.
General liability
Third-party bodily injury and property damage. It is the line nearly every contract names by default.
Without it — Loading damage at a dealership or an auction is a premises claim as much as a cargo one.
Umbrella & excess liability
Extra limit stacked above general liability, auto and employers liability. Usually the cheapest million dollars on the policy.
Without it — Highway severity plus a high-value load is the combination that exhausts primary limits.
Workers compensation
Required in almost every state the moment you have employees. Priced on payroll and class code, which is why the class code is worth arguing about.
Without it — Loading and tie-down is the injury exposure, not the driving.
Trailer interchange
Damage to a trailer you are pulling but do not own, while it is in your possession under a written interchange agreement. Your own physical damage coverage follows equipment you own, so an interchanged trailer is unprotected without it.
Without it — Equipment pulled under an interchange agreement is not covered by your own physical damage.

Lori Adams, TRS
Commercial Trucking Insurance Advisor
Twenty-five years in trucking insurance. Knows the filings, the radius rules and the carriers that will actually take the risk.
Transportation Risk Specialist (TRS)
What the insurance company will ask about your auto hauling business
We read the applications the markets use for businesses in this field and pulled out what they actually ask. Have these answers ready and a quote takes a day instead of a week, because nobody has to come back to you for the missing piece.
About the business
- What commodities do you haul?
- How many years have you been in business?
- Do you own any other businesses?
- What is your annual revenue?
How you operate
- Do you haul full truckloads or less than truckload?
- What percentage of your loads come through freight brokers versus contracts?
- What percentage of your loads go to regular fixed destinations?
- What states and major cities do you travel into or through?
- Do you haul any hazardous materials?
Safety and controls
- Are your vehicles equipped with GPS, cameras, or other tracking devices?
- Do you have any ownership, management, or name changes in the past five years?
- Do you lease trucks to other operators?
Your history
- List all losses and accidents from the last three years
- What insurance companies have covered you in the last three years?
Money and people
- What is your annual mileage?
- How many drivers do you have?
- What cargo limit do you need per truck?
Have these ready
- Your vehicle information including year, make, model, and current value for each truck and trailer
- Three years of loss runs from your current and prior insurance companies
- Driver records including dates they earned their CDL
- Any contracts that require specific insurance coverage
You answer what you can; a licensed agent fills the rest with you.
What our auto hauling clients ask us.
What cargo limit do I actually need?
Work it back from a full load at the values you actually haul. Nine ordinary vehicles will exceed a $100,000 cargo limit comfortably, and a single load of late-model trucks or anything exotic can exceed $250,000 on its own. Brokers increasingly require limits that reflect this, and the gap between your limit and the load is money you owe personally.
Am I covered for damage I cause loading?
Usually under cargo rather than liability, and the form matters. Some exclude damage from improper loading or securement, which is exactly how most auto transport damage happens. Scratches, tie-down damage and door dings are frequency claims in this class, and a policy that excludes them leaves you paying every one.
Do you write open and enclosed?
Both. Enclosed haulers usually carry higher-value loads and need limits to match, and the exotic and collector market is its own underwriting conversation. Tell us the highest value you would put on the trailer, not the average, because the limit has to be built for the worst load rather than the typical one.
Can a new authority get car hauler insurance?
Sometimes, and the market is narrow. Auto hauling is one of the classes several new-venture programs exclude by name, so the placement leans on driving experience hauling cars for someone else and on a cargo limit that matches the vehicles you carry. Dealer and transporter programs that say new ventures considered are written for dealers, not for a motor carrier authority, so read that line carefully.
What insurance does Central Dispatch require?
Central Dispatch does not publish a dollar minimum. Its terms of use require carriers to maintain the insurance, licenses and bonds their operation legally needs, it checks that operating authority and valid insurance are on file before a carrier is activated, and it says it monitors insurance status on an ongoing basis. The limits that matter come from the other side of the load: the brokers, dealers and auction houses you haul for set their own cargo requirements, and shippers are told to ask to be named as certificate holder. So the practical answer is the federal auto liability minimum plus a cargo limit built from a full load, with a certificate your agent can issue the day a shipper asks for it.
What does a auto hauling insurance application ask for?
The applications for auto hauling businesses ask about 4 things above all: what commodities do you haul; do you haul full truckloads or less than truckload; are your vehicles equipped with gps, cameras, or other tracking devices; list all losses and accidents from the last three years. Have your vehicle information including year, make, model, and current value for each truck and trailer and three years of loss runs from your current and prior insurance companies ready and a quote takes a day instead of a week.
Commercial insurance is 96% of what we do — it is not a department here, it is the whole business. Not ready to talk? The guides answer the questions this page raises in more depth. Already insured with us and need a certificate or a policy change? Ask the service team rather than starting a quote — it is faster and it goes to the people whose job it is. We also write home and auto, which is usually cheaper alongside the business policy than apart from it.
Handed a lease, a vendor packet or a client contract with insurance requirements? Paste it into the COI Requirements Decoder to see what each one means for your business, or read what the requirements mean.