
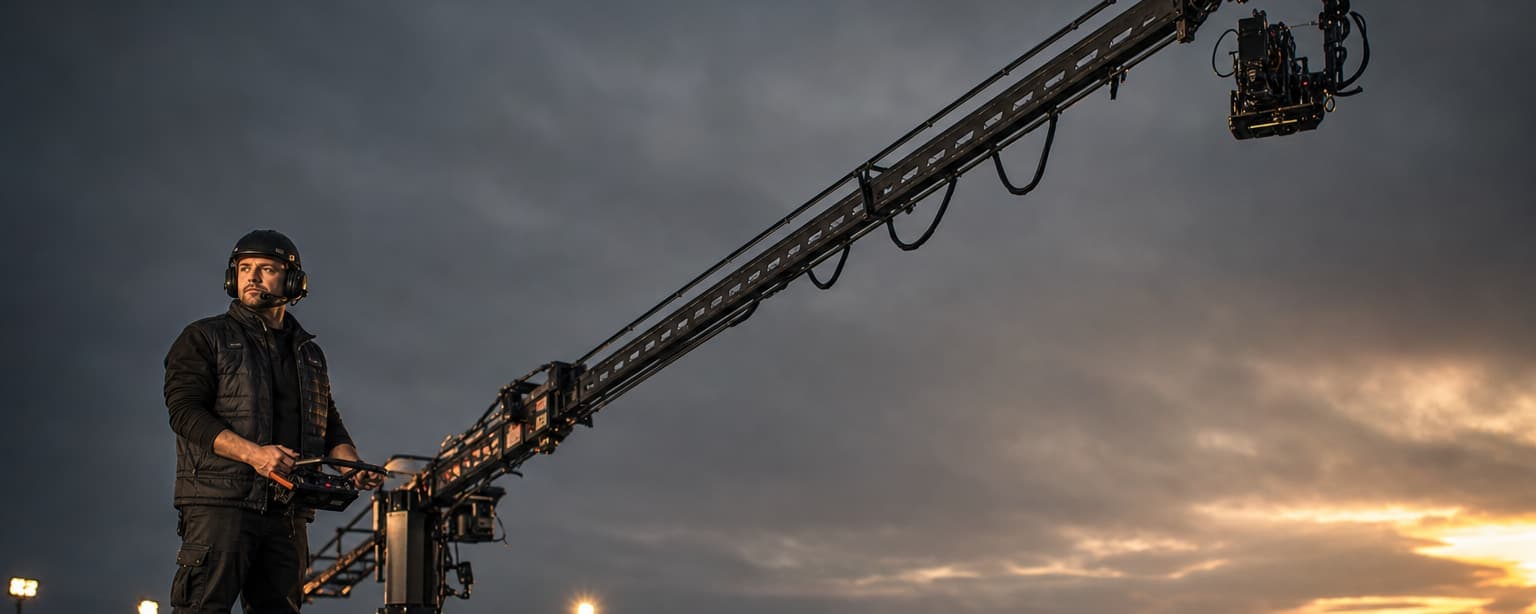
The load leaves the ground and everything under it is your problem.
Commercial insurance for crane, rigging and steel erection contractors, written around the lift itself, the equipment on it, and the contract you signed before the boom went up.
Tell us the situation.
One licensed human replies the same business day — not five agents, not an auto-responder. If the policy you have is already the right one, we will tell you.
We use this to quote and service your insurance, and we do not sell it or pass it to lead networks. Privacy policy.
Send us what you have. We’ll tell you if it’s right.
Your current policy paperwork, a renewal notice, or nothing at all. A licensed agent reads it and replies the same business day.
What crane and rigging businesses actually need.
General liability
Third-party bodily injury and property damage. It is the line nearly every contract names by default.
Without it — A dropped or swung load damages property that was never part of your job, and the people underneath it were not your employees.
Workers compensation
Required in almost every state the moment you have employees. Priced on payroll and class code, which is why the class code is worth arguing about.
Without it — Struck-by and caught-between are the fatality classes of this trade, and comp is the line that pays for them.
Inland marine & equipment
Tools, equipment and property in transit. It picks up exactly where commercial property stops, which is the moment the item leaves the building.
Without it — The crane itself is usually the largest single asset the business owns, and it moves between sites on public roads.
Commercial auto
Vehicles the business owns and the people who drive them for work.
Without it — A boom truck is a vehicle when it is driving and a machine when it is lifting, and the two are not covered by the same thing.
Equipment breakdown & spoilage
Covers the walk-in, the compressor and the line when they fail from the inside. A mechanical or electrical breakdown is excluded by property policies, and the stock that thawed goes with it.
Without it — Hydraulic and electrical failure stops the lift, and the standby cost falls on somebody.
Umbrella & excess liability
Extra limit stacked above general liability, auto and employers liability. Usually the cheapest million dollars on the policy.
Without it — A dropped load reaches numbers a primary limit was never sized for, and the contract usually names one.
Contractors pollution liability
Bodily injury, property damage and clean-up caused by a pollutant your work released: chemical drift, run-off, fuel spills. The standard general liability form excludes all of it.
Without it — A hydraulic burst on a finished surface or into a drain is a pollution claim before it is a property one.
Surety bonds
License, bid and performance bonds. A bond guarantees you will finish the job. It protects the other party, not you, which is the part most people get wrong.
Without it — Public and industrial work is bonded work, and the bond decides which contracts can be bid.
Business income
Replaces the profit and pays the ongoing bills while a covered loss keeps you closed. It is the part of a fire claim that is not the building.
Without it — One crane out of service is one crew idle and a schedule of lifts that has to be re-booked.
What the insurance company will ask about your crane and rigging business
We read 1 application the markets use for this kind of business and pulled out what they actually ask. Have these answers ready and a quote takes a day instead of a week, because nobody has to come back to you for the missing piece.
About the business
- What types of crane and rigging work do you do (crane rental with operator, bare crane rentals, rigging, steel erection, millwright work, or other)?
- What percentage of your work is commercial versus residential?
- How do you break down your annual income across different types of work?
- What industries or types of customers make up most of your business?
- Are you an AISC member for steel fabrication work?
How you operate
- What is the typical weight of items you lift, and what is your average and maximum on-hook value?
- Do you use load charts for all lifts?
- Are boom angle indicators on your equipment and actually used?
- Do you perform dual or tandem lifts, and if so, how do you coordinate them?
- How do you communicate with your team during lifts?
Safety and controls
- What is your minimum age requirement for operators?
- How do you screen or check references for new operators?
- Are your operators and crew members union or non-union?
- Do you conduct regular safety meetings with your employees?
- Do you have a safety manager responsible for your safety program?
Your history
- Have you had any losses over $5,000 in the past five years?
- What losses or claims has your company had in the past five years?
Money and people
- How many crane operators do you have?
- How many oilers do you have?
- How many other employees do you have?
- How much do you spend annually on renting or leasing equipment from other companies?
- Do you use standard written contracts with your clients?
Have these ready
- Your last five years of claims history from your current insurer, called loss runs, showing carrier name, policy term, number of claims, open claims, and amounts paid and reserved
- A copy of your standard rental agreement or job ticket that shows what insurance your clients must have
- A copy of your written crane inspection form
- A list of all your crane operators with their dates of birth and whether they are licensed or certified
- A copy of any warranty you provide on used equipment you sell
You answer what you can; a licensed agent fills the rest with you.
What our crane and rigging clients ask us.
Is the crane covered while it is lifting, or only while it is driving?
Two different policies, and this is the one that catches people. A boom truck is a vehicle when it is driving, covered by commercial auto, and a machine when it is set up and lifting, covered by inland marine. A gap between the two is how a claim ends up with nobody paying it.
What does a contract usually require from a crane company?
Higher limits than most trades and a longer list of endorsements: additional insured on a primary and non-contributory basis, waiver of subrogation, and frequently an umbrella at five or ten million because of what a dropped load can reach.
Do you cover bare rental, where somebody else operates it?
Yes, and it is worth flagging at quote because it changes the risk completely. Renting the crane with your operator and renting it bare are different exposures, and the contract usually decides who carries the liability rather than the policy.
What about riggers liability?
Ask for it by name. Property in your care while it is being lifted is excluded by general liability under the care, custody and control exclusion, and riggers liability is the coverage that answers it.
What does a crane and rigging insurance application ask for?
The applications for crane and rigging businesses ask about 4 things above all: what types of crane and rigging work do you do (crane rental with operator, bare crane rentals, rigging, steel erection, millwright work, or other); what is the typical weight of items you lift, and what is your average and maximum on-hook value; what is your minimum age requirement for operators; have you had any losses over $5,000 in the past five years. Have your last five years of claims history from your current insurer, called loss runs, showing carrier name, policy term, number of claims, open claims, and amounts paid and reserved and a copy of your standard rental agreement or job ticket that shows what insurance your clients must have ready and a quote takes a day instead of a week.
Commercial insurance is 96% of what we do — it is not a department here, it is the whole business. Not ready to talk? The guides answer the questions this page raises in more depth. Already insured with us and need a certificate or a policy change? Ask the service team rather than starting a quote — it is faster and it goes to the people whose job it is. We also write home and auto, which is usually cheaper alongside the business policy than apart from it.
Handed a lease, a vendor packet or a client contract with insurance requirements? Paste it into the COI Requirements Decoder to see what each one means for your business, or read what the requirements mean.