
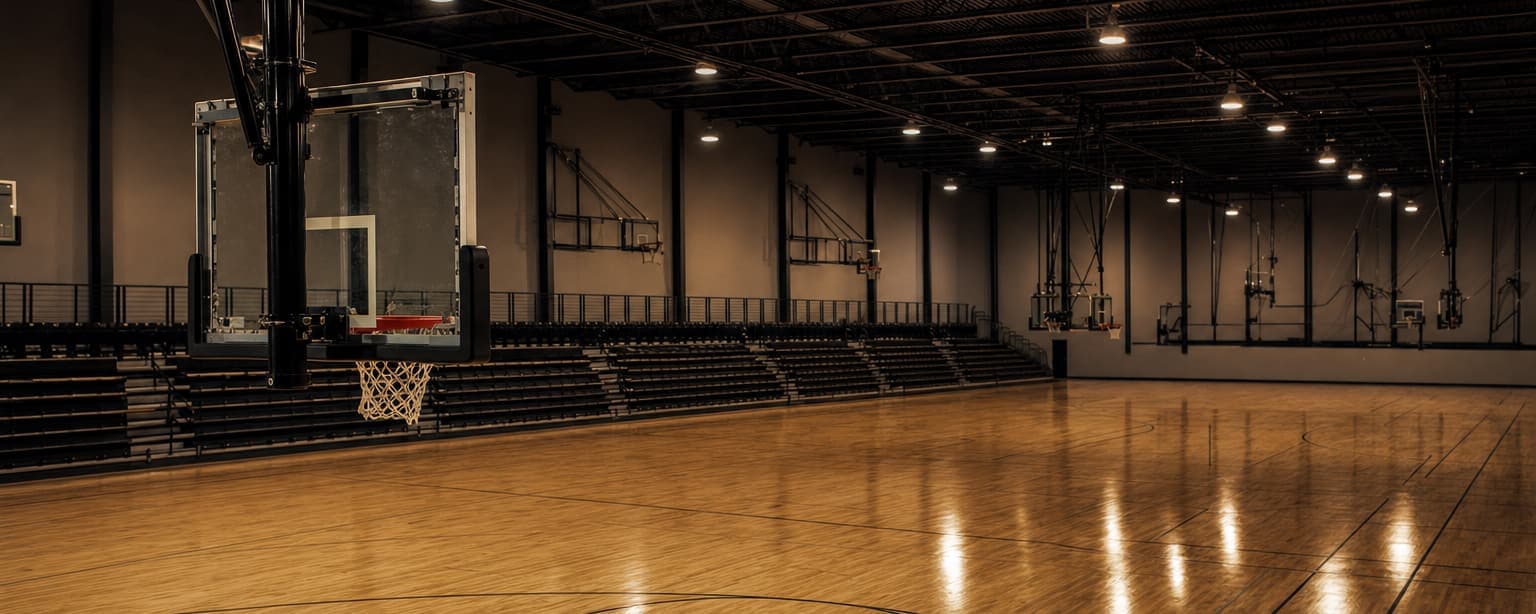
You own the building and everyone else’s activity happens inside it.
We insure sports complexes, field houses and training facilities: the property, the participants, and the constant stream of leagues, camps and hirers using your floor.
Tell us the situation.
One licensed human replies the same business day — not five agents, not an auto-responder. If the policy you have is already the right one, we will tell you.
We use this to quote and service your insurance, and we do not sell it or pass it to lead networks. Privacy policy.
Send us what you have. We’ll tell you if it’s right.
Your current policy paperwork, a renewal notice, or nothing at all. A licensed agent reads it and replies the same business day.
What sports facility businesses actually need.
Commercial property
Buildings and contents, valued at what it costs to rebuild today rather than what you paid.
Without it — The building, the surface, the equipment and the fit-out are the business.
General liability
Third-party bodily injury and property damage. It is the line nearly every contract names by default.
Without it — Participants, spectators and everyone visiting a building built for collisions.
Participant accident
Pays the medical costs of a player, a camper or a rider injured while taking part, without anyone having to establish that the organization was at fault.
Without it — Injuries in ordinary play, covered without a fault argument that would name you.
Tenant user liability
A program that lets a venue sell short-term liability coverage to the people hiring it, so a facility can require insurance without turning away every hirer who has none.
Without it — A program that insures every hirer to your standard instead of you reviewing their certificates.
Business income
Replaces the profit and pays the ongoing bills while a covered loss keeps you closed. It is the part of a fire claim that is not the building.
Without it — A closed floor loses the leagues, the camps and the memberships at once.
Sexual abuse & molestation
Covers allegations of abuse by staff or volunteers. General liability usually excludes it outright, and any organization working with children, patients or vulnerable adults will be asked to carry it by name.
Without it — Youth programs in your building are your exposure as well as theirs.
Liquor liability
If you serve alcohol, your general liability almost certainly excludes what happens after you serve it.
Without it — A bar, a tournament license or a hosted event changes the risk entirely.
Equipment breakdown & spoilage
Covers the walk-in, the compressor and the line when they fail from the inside. A mechanical or electrical breakdown is excluded by property policies, and the stock that thawed goes with it.
Without it — Refrigeration on an ice sheet, HVAC in a dome, lighting on a turf field.
What the insurance company will ask about your sports facility business
We read 3 applications the markets use for this kind of business and pulled out what they actually ask. Have these answers ready and a quote takes a day instead of a week, because nobody has to come back to you for the missing piece.
About the business
- What year did you start this fitness center?
- What is your annual gross revenue?
- Is the building owned, leased, or rented?
- What is the total square footage of your facility?
How you operate
- Describe what services and equipment you offer (for example, weights, cardio, classes, personal training, tanning, massage, pools, hot tubs, saunas, courts)
- Are members required to sign a liability release or waiver when they join?
- Do you allow children under 12 to use the facility or take classes?
- Are all your fitness staff and personal trainers required to have CPR certification?
- Is the facility staffed during all hours it is open to members?
Safety and controls
- Are warning signs posted throughout the facility?
- Do you have a burglar alarm system (local, central station, or none)?
- Does the building have circuit breakers for the electrical system?
- If the building was built before 1978, does it have aluminum wiring or knob-and-tube wiring?
- Do you perform criminal and background checks on employees?
Your history
- Have you or any owner had any criminal convictions or pending charges in the past five years?
- Why are you seeking new insurance coverage?
- Have there been any claims, incidents, or allegations of abuse or molestation at your facility?
Money and people
- How many stories is the building?
- What year was the building constructed?
- Do you operate any other business besides this fitness center?
- Do you have independent contractors at your facility?
Have these ready
- Your five-year loss and claims history with details
- Copies of any contracts with clients or landlords
- Certificates of insurance from independent contractors
- Service and maintenance logs for fitness equipment and facility systems
- Proof that personal trainers and instructors are certified
You answer what you can; a licensed agent fills the rest with you.
What our sports facility clients ask us.
Should we require insurance from every group that rents from us?
Yes, and the practical question is how. Requiring certificates means refusing bookings from groups that cannot produce one and having staff assess documents they are not qualified to read. A tenant user program sells compliant coverage to each hirer directly, so every booking is insured to a standard you set and nobody on your team is underwriting. For a facility with constant short-term hire it is the difference between a policy and a process.
We host tournaments. Does that need something extra?
Usually, because a tournament is an event rather than ordinary operations: more people, visiting teams, occasionally alcohol, sometimes vendors, and often a sanctioning body with its own insurance requirements. Declare tournament activity rather than letting it sit inside general operations: the difference is what an underwriter would want to know, and what a claim would examine.
What drives our premium most?
The activities on the floor and the age of the people doing them. Contact sports, height, ice, water and anything with a machine rate higher than court sports. Youth programming brings abuse and molestation into the center of the underwriting. Square footage and revenue set the scale; the activity mix sets the rate, and a precise description of it is worth real money.
What does a sports facility insurance application ask for?
The applications for sports facility businesses ask about 4 things above all: what year did you start this fitness center; describe what services and equipment you offer (for example, weights, cardio, classes, personal training, tanning, massage, pools, hot tubs, saunas, courts); are warning signs posted throughout the facility; have you or any owner had any criminal convictions or pending charges in the past five years. Have your five-year loss and claims history with details and copies of any contracts with clients or landlords ready and a quote takes a day instead of a week.
Commercial insurance is 96% of what we do — it is not a department here, it is the whole business. Not ready to talk? The guides answer the questions this page raises in more depth. Already insured with us and need a certificate or a policy change? Ask the service team rather than starting a quote — it is faster and it goes to the people whose job it is. We also write home and auto, which is usually cheaper alongside the business policy than apart from it.
Handed a lease, a vendor packet or a client contract with insurance requirements? Paste it into the COI Requirements Decoder to see what each one means for your business, or read what the requirements mean.