
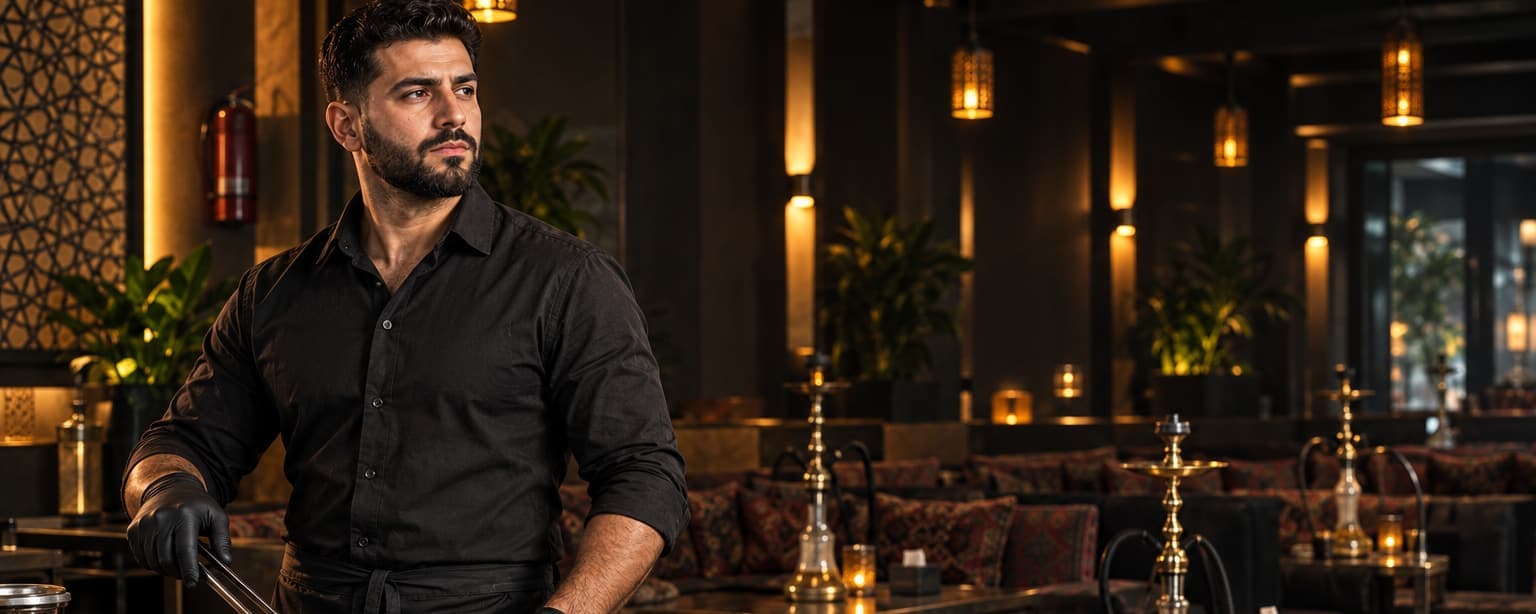
Who insures hookah lounges, and what will the underwriter ask?
Mostly surplus lines carriers, reached through a licensed agent and a wholesale broker, because hot coals add a fire exposure that many standard bar and restaurant programs will not take. Expect questions about how coals are lit, held and put out, whether you serve alcohol and how much of your sales it is, your hours, and whether your state lets you allow smoking indoors at all. On our 2026 calls a new lounge was quoted between $12,500 and a $20,000 minimum for general and liquor liability together.
Tell us the situation.
One licensed human replies the same business day — not five agents, not an auto-responder. If the policy you have is already the right one, we will tell you.
We use this to quote and service your insurance, and we do not sell it or pass it to lead networks. Privacy policy.
Brian Victores
Commercial Insurance Advisor
Licensed in nearly every state, working contractors and small commercial, writing general liability, workers comp and commercial auto. Runs on the principle that the best insurance experience is a boring one: straight answers, fast quotes, no surprises.
Send us what you have. We’ll tell you if it’s right.
Your current policy paperwork, a renewal notice, or nothing at all. A licensed agent reads it and replies the same business day.
The detail
Florida’s Clean Indoor Air Act prohibits smoking in enclosed indoor workplaces but lists exceptions, including a retail tobacco shop and a stand-alone bar.
Florida Statutes section 386.2045, enclosed indoor workplaces; specific exceptions
Florida defines a retail tobacco shop as a workplace "dedicated to or predominantly for the retail sale of tobacco, tobacco products, and accessories for such products, in which the sale of other products or services is merely incidental."
A Florida stand-alone bar must derive "no more than 10 percent of its gross revenue from the sale of food consumed on the licensed premises" and may not share a common entryway or indoor area with another enclosed workplace.
The surplus lines market exists for "covering risks not available within the admitted market," and a "licensed surplus lines broker is responsible for ensuring the surplus lines insurer meets eligibility criteria."
National Association of Insurance Commissioners, Surplus Lines (CIPR topic page)
On a Florida bar and hookah lounge in 2026, the first underwriter’s price came back around $20,000 while the landlord waited on proof of insurance, and general liability alone was priced higher than general and liquor liability together because of the hookah exposure.
Boring Insurance call records and policy files, 2025 to October 2026 (clients and carriers unnamed unless named positively)
A New Jersey hookah lounge of about 15,000 square feet came to us in 2026 for general and liquor liability only, and our producer had placed a hookah lounge with liquor sales before, through the wholesale market.
Boring Insurance call records and policy files, 2025 to October 2026 (clients and carriers unnamed unless named positively)
Hookah underwriters typically ask how coals are lit and where hot coals sit between servings, how ash is disposed of, whether the lounge serves food and alcohol, its hours, and whether local law permits indoor smoking at the location.
Kevin Kelsey, agency placement experience
What this means for you
- Check your state’s indoor smoking law before you sign the lease. In Florida a lounge with a real kitchen may fit neither exception: a stand-alone bar can take no more than 10% of its revenue from food, and a tobacco shop’s other sales must be incidental. Underwriters ask the same question, because a lounge outside its smoking law has a regulatory problem on top of a fire one.
- Write down how you handle coals. Where they are lit, what they sit in between bowls, who moves them and where the ash goes. A one-page procedure answers half the underwriter’s questions before they are asked.
- If you serve alcohol, ask for general and liquor liability together. On our Florida account the package priced better than general liability alone, and some underwriters will not write the general liability without the liquor.
- Budget for a minimum premium. Hookah lounges are a small class, so carriers that write them set minimums. Our 2026 quotes for a new lounge ran from $12,500 to a $20,000 minimum, and one market that had written the class at $7,500 the year before had repriced it.
Go deeper on any of these
Related questions
- Will a standard bar or restaurant program cover a hookah lounge?
Usually not. In our experience most standard programs decline the class or exclude the smoking exposure, which is why these accounts go to surplus lines carriers through a wholesaler. Telling every market about the hookah up front saves a decline after a quote.
- Do we need liquor liability if hookah is the main business?
Yes, if you sell or serve alcohol at all. The general liability form excludes alcohol claims for any business in the business of selling or serving it, however small the bar is next to the hookah menu.
- General liability without liquor liability
- What if the surplus lines carrier goes broke?
Surplus lines policies are generally outside state guaranty funds. Florida makes the insured sign an acknowledgment saying so before the policy is placed. The trade-off is access: the admitted market mostly will not write the class.
- Do you insure hookah lounges?
Yes, through the wholesale market, alongside bars and nightclubs. Send your hours, the alcohol share of your sales and your coal procedure with the first request and we can go to the right markets once.
- Nightclub and lounge insurance
Need this handled?
Reading about it and having it handled are different jobs, and the second one is ours. We place the accounts other brokers decline — claims history, a cancellation, an unusual operation, a business nobody wants to underwrite twice — and we will tell you when the policy you already have is the right one. Tell us the situation and a licensed human replies the same business day.
Written by the licensed brokers at Boring Insurance. Last updated 2026-10-07. See all guides.