
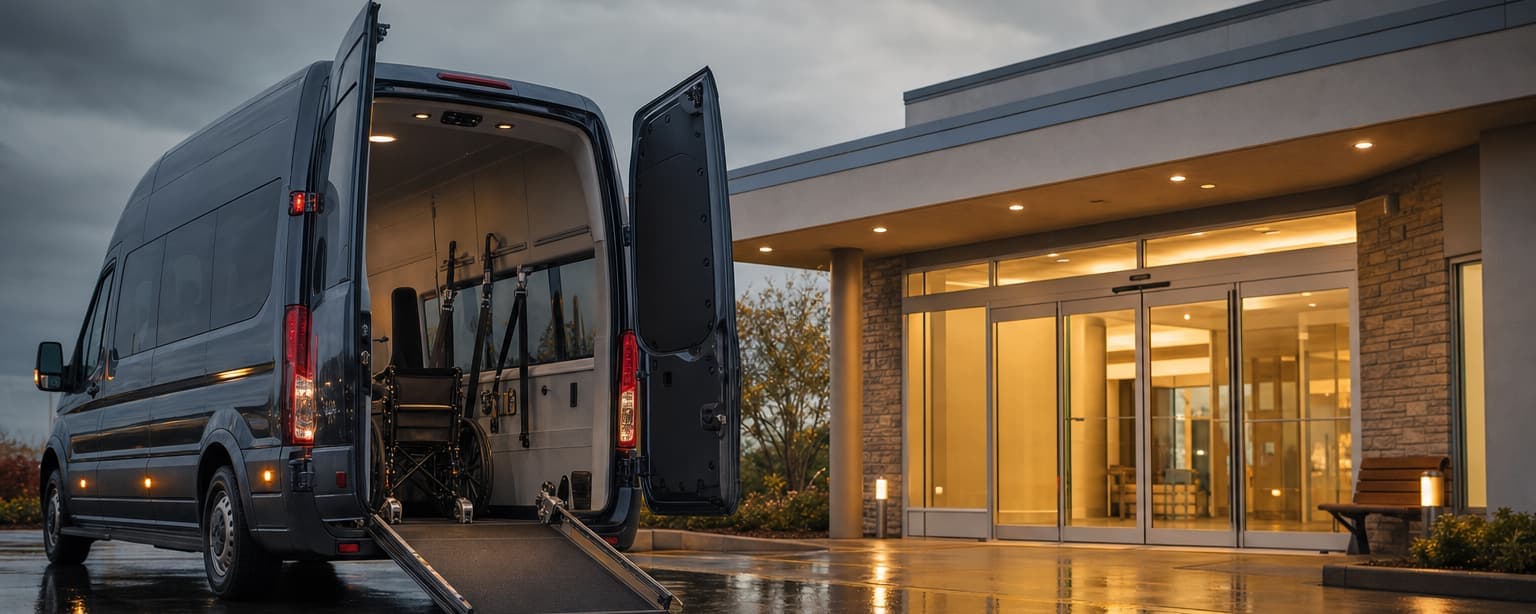
The hardest public auto class to place, and the fastest growing.
We insure NEMT and paratransit operators for wheelchair transport, broker contracts, and the abuse exposure that comes with transporting vulnerable riders.
Tell us the situation.
One licensed human replies the same business day — not five agents, not an auto-responder. If the policy you have is already the right one, we will tell you.
We use this to quote and service your insurance, and we do not sell it or pass it to lead networks. Privacy policy.
Send us what you have. We’ll tell you if it’s right.
Your current policy paperwork, a renewal notice, or nothing at all. A licensed agent reads it and replies the same business day.
What non-emergency medical transport businesses actually need.
Commercial auto
Vehicles the business owns and the people who drive them for work.
Without it — Wheelchair-equipped vehicles carrying non-ambulatory passengers are the highest-rated units in public auto.
Sexual abuse & molestation
Covers allegations of abuse by staff or volunteers. General liability usually excludes it outright, and any organization working with children, patients or vulnerable adults will be asked to carry it by name.
Without it — Transporting elderly, disabled and cognitively impaired passengers one-to-one is an allegation exposure with no witness, and general liability excludes it.
General liability
Third-party bodily injury and property damage. It is the line nearly every contract names by default.
Without it — Loading, securement and assistance in and out of the vehicle happen off the road and outside the auto policy.
Workers compensation
Required in almost every state the moment you have employees. Priced on payroll and class code, which is why the class code is worth arguing about.
Without it — Lifting, transferring and securing passengers and wheelchairs is where drivers are injured.
Umbrella & excess liability
Extra limit stacked above general liability, auto and employers liability. Usually the cheapest million dollars on the policy.
Without it — Broker and authority contracts routinely require limits above primary before you can be credentialed.
Professional liability
Covers the advice, the drawing, the diagnosis. The work itself, rather than someone getting hurt on your premises.
Without it — Where staff render any care beyond transport, the standard applied is a clinical one.
Auto physical damage
Damage to your own tractor and trailer. Primary liability pays for what you do to everyone else and nothing for your equipment, so without this a rollover you caused leaves you paying off a truck you can no longer run.
Without it — A wheelchair conversion costs far more than the van it is built on.

Lori Adams, TRS
Commercial Trucking Insurance Advisor
Twenty-five years in trucking insurance. Knows the filings, the radius rules and the carriers that will actually take the risk.
Transportation Risk Specialist (TRS)
What the insurance company will ask about your non-emergency medical transport business
We read the applications the markets use for businesses in this field and pulled out what they actually ask. Have these answers ready and a quote takes a day instead of a week, because nobody has to come back to you for the missing piece.
About the business
- What type of transportation services do you provide, and where do you operate?
- When did you start this business?
- Is this a new business, or have you been operating for a while?
- How would you describe your business structure (sole owner, partnership, corporation)?
- Do you operate in more than one state?
How you operate
- How far do your typical trips go, and what's the farthest distance you operate?
- Do you transport passengers for ride-share apps like Uber or Lyft?
- Do you use rented vehicles for any of your trips?
- What percentage of your trips are subcontracted to other companies?
- Do you transport any special passengers, such as those with oxygen tanks, wheelchairs, or pregnant women?
Your drivers
- How many full-time drivers, part-time drivers, and backup drivers do you have?
- Do you hire employees or use independent contractors?
- What's your driver turnover rate each year?
- How often do you order driver records from the DMV?
- What are your hiring standards for drivers?
Safety and controls
- Do your vehicles have cameras installed? If so, are they one-way or two-way?
- Are any vehicles equipped with lights or sirens?
- Do your drivers take vehicles home? If yes, can they use them personally?
- Are all your drivers trained in wheelchair securement equipment if you transport wheelchairs?
- Do you have procedures in place to review accidents?
Your history
- Why are you looking for new insurance?
- Has your current insurance company offered to renew your policy?
- Have you or the business ever had an insurance claim or lawsuit?
- Have you ever been investigated or disciplined by a government agency or hospital?
- Are you aware of any incidents that could lead to a future claim?
Have these ready
- Your current insurance information and coverage details for the last three years, including any claims
- Your loss and claims history for the last five years from your current insurer (called loss runs)
- How many vehicles you have and how many are equipped with lifts or ramps
- A list of all owners and decision-makers with their contact information
- Any contracts you have with other companies or clients
You answer what you can; a licensed agent fills the rest with you.
What our non-emergency medical transport clients ask us.
Why is NEMT so expensive to insure?
Everything about it raises the rate at once. Passengers are non-ambulatory or medically fragile, so an ordinary collision produces a worse injury. The vehicles are converted and cost more to repair. The work is urban, high-stop and schedule-driven. Driver turnover is high, in a class where the driver is alone with a vulnerable passenger. Wheelchair-equipped work sits in a higher tier for those reasons.
What do transportation brokers require?
It varies by broker and by state Medicaid program, but expect specified auto liability limits, general liability, workers compensation, abuse and molestation, and the broker named as an additional insured with notice of cancellation. Credentialing is refused without the certificate, so the insurance is a precondition of the revenue rather than an overhead against it. Send the credentialing packet and we will match it.
Do you write new NEMT ventures?
Yes, and the first year is the expensive one, because no claims history means the price carries the uncertainty, and it typically improves materially after twelve clean months. What helps most at the start is documented driver screening, annual MVR checks, a securement training record and cameras. Underwriters in this class reward controls more than most.
Is abuse coverage really necessary for transport?
Yes, and it is one of the clearest cases in the class. A driver alone in a vehicle with a passenger who may have cognitive impairment, and who may not be able to give a reliable account, is the fact pattern these allegations arise from. General liability excludes it, brokers require it, and it is what defends the operator as well as protecting the passenger.
What does a non-emergency medical transport insurance application ask for?
The applications for non-emergency medical transport businesses ask about 4 things above all: what type of transportation services do you provide, and where do you operate; how far do your typical trips go, and what's the farthest distance you operate; how many full-time drivers, part-time drivers, and backup drivers do you have; do your vehicles have cameras installed? if so, are they one-way or two-way. Have your current insurance information and coverage details for the last three years, including any claims and your loss and claims history for the last five years from your current insurer (called loss runs) ready and a quote takes a day instead of a week.
Commercial insurance is 96% of what we do — it is not a department here, it is the whole business. Not ready to talk? The guides answer the questions this page raises in more depth. Already insured with us and need a certificate or a policy change? Ask the service team rather than starting a quote — it is faster and it goes to the people whose job it is. We also write home and auto, which is usually cheaper alongside the business policy than apart from it.
Handed a lease, a vendor packet or a client contract with insurance requirements? Paste it into the COI Requirements Decoder to see what each one means for your business, or read what the requirements mean.