
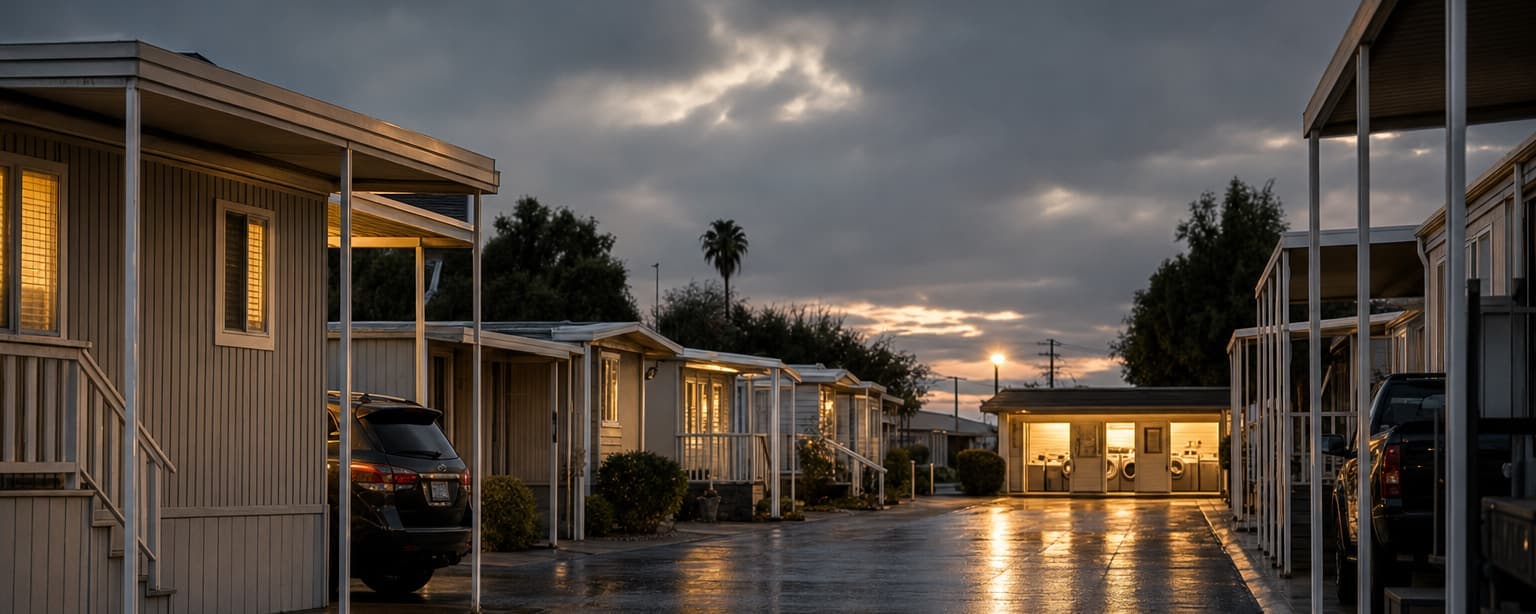
You own the land, the roads and the utilities. Mostly you do not own the homes.
You are responsible for the land under homes you do not own. We cover park owners for that, for the infrastructure, and for liability across the community you control.
Tell us the situation.
One licensed human replies the same business day — not five agents, not an auto-responder. If the policy you have is already the right one, we will tell you.
We use this to quote and service your insurance, and we do not sell it or pass it to lead networks. Privacy policy.
Send us what you have. We’ll tell you if it’s right.
Your current policy paperwork, a renewal notice, or nothing at all. A licensed agent reads it and replies the same business day.
What mobile home park businesses actually need.
Site infrastructure
Roads, utilities, water and sewer lines, lighting, clubhouse and park-owned buildings.
Without it — Buried utilities are the asset owners forget to schedule.
Premises liability
Injury on roads, in common areas, at the pool and the playground.
Without it — You control the common realm of a residential community.
Park-owned homes
Any units you own and rent out, which are a different exposure from rented lots.
Without it — Lot rent and home rent are two businesses on one site.
Loss of lot rent
Income while lots cannot be occupied after a covered loss.
Without it — A tornado or wildfire empties a park faster than it damages the ground.
Habitability and fair housing
Resident claims over conditions, utilities, rules and evictions.
Without it — A heavily regulated residential relationship, and not a property claim.
What our mobile home park clients ask us.
Do I insure the homes?
Only the ones you own. In most parks residents own their homes and rent the lot, so their homes are their responsibility and should be insured by them, worth requiring in the lease and verifying, because an uninsured destroyed home tends to become the park’s problem practically even when it is not legally. Park-owned homes you rent out are your property and need scheduling individually.
What drives the price of a park?
Catastrophe exposure and the age of the stock, mostly. Manufactured homes perform badly in wind, so tornado and hurricane regions rate hard and tie-down standards matter. Then the age of the homes and whether pre-1976 units are present, the condition of utilities you own, and whether there is a pool or playground. Occupancy and lot-rent stability matter too: a half-empty park with deferred maintenance is a harder placement than a full one.
What is the liability exposure I am most likely to underestimate?
The utilities and the roads. You own the water and sewer lines, and a contamination or backup event affecting multiple homes is a large multi-claimant loss. Private roads inside the park are yours for maintenance and for accidents on them. Both are more likely than the pool claim owners tend to worry about, and both are worth checking are actually scheduled rather than assumed to fall under "the site".
Commercial insurance is 96% of what we do — it is not a department here, it is the whole business. Not ready to talk? The guides answer the questions this page raises in more depth. Already insured with us and need a certificate or a policy change? Ask the service team rather than starting a quote — it is faster and it goes to the people whose job it is. We also write home and auto, which is usually cheaper alongside the business policy than apart from it.
Handed a lease, a vendor packet or a client contract with insurance requirements? Paste it into the COI Requirements Decoder to see what each one means for your business, or read what the requirements mean.