
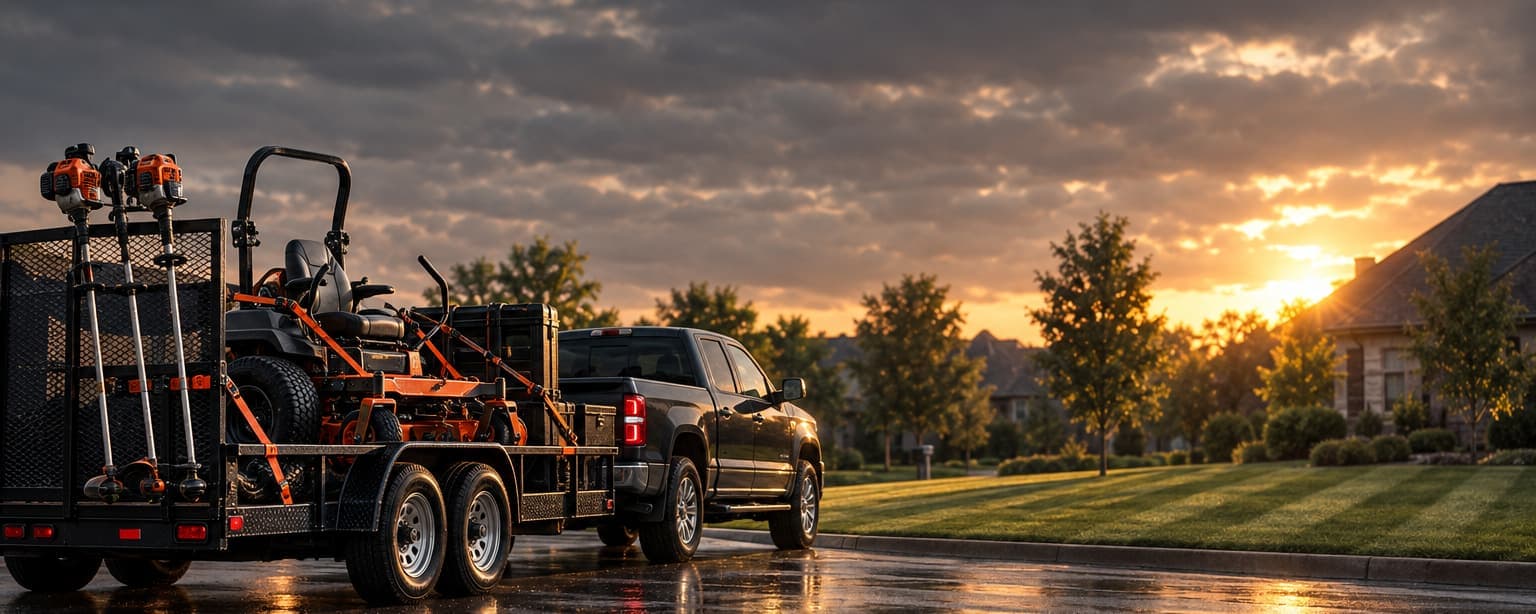
A mower throws a rock through a window every week somewhere. The policy is cheaper than the window.
Lawn care is one of the most common small businesses in the country and one of the easiest to insure well, because the exposures are known: a thrown object from a mower, a chemical applied wrongly, a trailer and a truck on the road all day, and a crew that gets hurt. General liability, commercial auto and workers compensation are the three policies, and the equipment floater is the fourth for anyone with more than a push mower. We place them for solo operators through multi-crew companies, and the application is short for a business that can describe its services plainly.
Tell us the situation.
One licensed human replies the same business day — not five agents, not an auto-responder. If the policy you have is already the right one, we will tell you.
We use this to quote and service your insurance, and we do not sell it or pass it to lead networks. Privacy policy.
Send us what you have. We’ll tell you if it’s right.
Your current policy paperwork, a renewal notice, or nothing at all. A licensed agent reads it and replies the same business day.
What lawn care business businesses actually need.
General liability
Injury and property damage from the work: a rock through a window or a windshield, a customer's dog let out, a sprinkler head or a buried line cut.
Without it — A commercial customer will not sign a service agreement without it, and the first thrown rock costs more than a year of premium.
Commercial auto
The trucks and the trailers, with the equipment on them, on the road between jobs.
Without it — A personal auto policy excludes business use, and a truck with a trailer and a company name on the door is business use on sight.
Workers compensation
Medical bills and lost wages for a crew member hurt on the job, and the employer's liability that goes with it.
Without it — Required from the first employee in most states, and the fastest way for a landscaper to lose a commercial contract is a certificate that does not show it.
Equipment (inland marine)
Mowers, trimmers, blowers and the trailer contents, against theft from the yard, the trailer or the job site.
Without it — Equipment on a trailer is not covered by the auto policy, and a stolen trailer full of mowers is a season's revenue.
Pesticide and herbicide applicator coverage
For businesses that spray: damage from a chemical applied wrongly, drifting or applied to the wrong lawn.
Without it — Standard general liability excludes pollution, and a lawn chemical is a pollutant the moment it lands where it should not.
What landscaping and lawn care companies we placed in 2025 and 2026 actually paid.
These are annual premiums from policies we bound, effective January 2025 to October 2026. We show the median and the middle half of what clients paid, never the cheapest or the most expensive, and only for lines where at least five businesses stand behind the figure.
- Commercial auto
- $7,920median a year
- Middle half: $3,150 to $12,240
- 16 policies from 10 businesses
- Workers compensation
- $1,940median a year
- Middle half: $1,530 to $2,580
- 17 policies from 14 businesses
- Business owners or package policy (property and liability together)
- $3,690median a year
- Middle half: $2,830 to $5,410
- 13 policies from 9 businesses
Payroll moves workers compensation more than anything else, and the services you provide, your limits and your claims history move the rest, so treat these as a sense of scale rather than a quote. Source: Boring Insurance bound policies, cancelled policies and test records excluded, refreshed 2026-10-04.
The claims we actually see.
Ordered by how often we see them, not by how dramatic they are. Each one names the coverage that answers it — and the policy people wrongly assume already does.
Most common
A mower throws a stone into a window, a car or a person
Covered by General liability
Small claims at a time, until the one that hits a person. The policy pays the windows so it is there for the person.
Common
A crew member is hurt by a mower or a trimmer
Covered by Workers compensation
A 1099 helper who is hurt is treated as an employee by the state in most cases, and the employer with no policy pays the medical bills and a penalty.
Common
A trailer detaches or a truck backs into a customer's vehicle
Covered by Commercial auto
The personal auto insurer denies business use and the claim comes back to the business.
Less common, severe
A herbicide kills a customer's lawn or a neighbor's garden
Covered by Applicator coverage, when bought
The pollution exclusion on plain general liability leaves the replanting bill with you.
Joe Gorman
Co-Founder | President of Commercial Lines
Came up in construction, on site and in the office, then moved into sales. Went out on a limb to become Boring’s first dedicated salesperson when the agency had no sales team at all, and now leads it. Landscaping is the class he writes most: grounds maintenance, tree work, irrigation and the spray operations that push an account out of preferred appetite.
What the policy will not cover.
Pick a procedure to see what the exclusion actually means and whether it can be placed somewhere else.
The application asks what services you offer because the standard lawn care rate assumes mowing, trimming and cleanup. Each of these is a separate answer and often a separate rate.
What a lawn care policy will not cover without being told
Tree work above ground level
Climbing, bucket trucks and removals are a tree service exposure with its own rates and its own application.
Can it be placed? Yes, on a tree service policy, which we also place.
Snow plowing
Excluded on many lawn care policies and rated separately, because a plow on a parking lot is a slip-and-fall exposure all winter.
Can it be placed? Yes, with the plowing contracts and the properties disclosed.
Hardscape and retaining walls
Building something that can fail is a contractor exposure, and the completed-operations coverage has to be priced for it.
Can it be placed? Yes, once the share of revenue from construction is known.
Chemicals without a license
Applicator coverage is written for licensed applicators; unlicensed spraying is uninsurable and, in most states, illegal.
Can it be placed? Yes, after the license.
What the insurance company will ask about your lawn care business business
We read 3 applications the markets use for this kind of business and pulled out what they actually ask. Have these answers ready and a quote takes a day instead of a week, because nobody has to come back to you for the missing piece.
About the business
- What services do you provide and what percentage of your work is residential versus commercial
- How long have you been in business
- What's your business structure: sole proprietorship, LLC, corporation, or partnership
- Do you belong to any industry associations or groups
How you operate
- How many full-time and part-time employees do you have
- What equipment do you use on the job, and what's your maintenance program
- Do you subcontract any work, and if so, what type
- Do you work more than 50 miles from your main location
- When utilities are available, do you contact them to locate underground lines before you start work
Safety and controls
- What records do you keep: work orders, bid agreements, accident reports, and billing documents
- Do you ask subcontractors to provide proof of liability insurance
- Do you limit your tree work to one story or below
Your history
- Who is your current insurance company, or your last one if you don't have coverage now
- Have you or anyone who owned this business before ever had a claim or loss
- In the last three years, has your insurance been cancelled, not renewed, or dropped for nonpayment
- In the last five years, have you or any owner personally had bankruptcy or unpaid tax judgments
Money and people
- What was your total annual gross income last year
- What is your total annual payroll
- Do you own or lease any equipment to rent or loan to others
Have these ready
- Your business name, mailing address, and current location address
- A list of all owned and leased equipment with manufacturer, model, year, and serial numbers
- Your last five years of claims history from your current insurer, called loss runs, with details of each claim
- Names and contact information for anyone who should be added to the policy as an additional insured
You answer what you can; a licensed agent fills the rest with you.
What our lawn care business clients ask us.
How much does lawn care insurance cost?
General liability for a solo mowing operation is inexpensive, often under a thousand dollars a year, and the total rises with each truck, each employee and each service added. Workers compensation is priced on payroll, commercial auto on the vehicles, and chemicals add a surcharge. A two-crew company with trucks and a spray license pays several times what the solo operator pays, and earns several times the revenue.
Do I need insurance for a lawn care business if I work alone?
Commercial customers and property managers require it, and residential customers increasingly ask. Beyond the contract, a mower is a machine that throws objects at speed near people, cars and windows, and the claim from that lands on you personally without a policy.
What does a lawn care insurance application ask for?
The landscaping applications we work from ask which services you provide and the share of revenue from each, whether you apply chemicals and hold the license, whether you do tree work, hardscape or snow removal, the number of employees and crews, the vehicles and trailers, the value of equipment, annual revenue, and five years of claims. A business that knows its service mix answers it in one sitting.
Does my personal auto policy cover my truck if I use it for lawn care?
Almost never. Personal auto policies exclude business use, and a truck towing a trailer of equipment to paying jobs is business use. A commercial auto policy covers the truck, the trailer and the liability of driving them for work, and it is the policy a customer's insurer will look for after an accident in their driveway.
Commercial insurance is 96% of what we do — it is not a department here, it is the whole business. Not ready to talk? The guides answer the questions this page raises in more depth. Already insured with us and need a certificate or a policy change? Ask the service team rather than starting a quote — it is faster and it goes to the people whose job it is. We also write home and auto, which is usually cheaper alongside the business policy than apart from it.
Handed a lease, a vendor packet or a client contract with insurance requirements? Paste it into the COI Requirements Decoder to see what each one means for your business, or read what the requirements mean.