
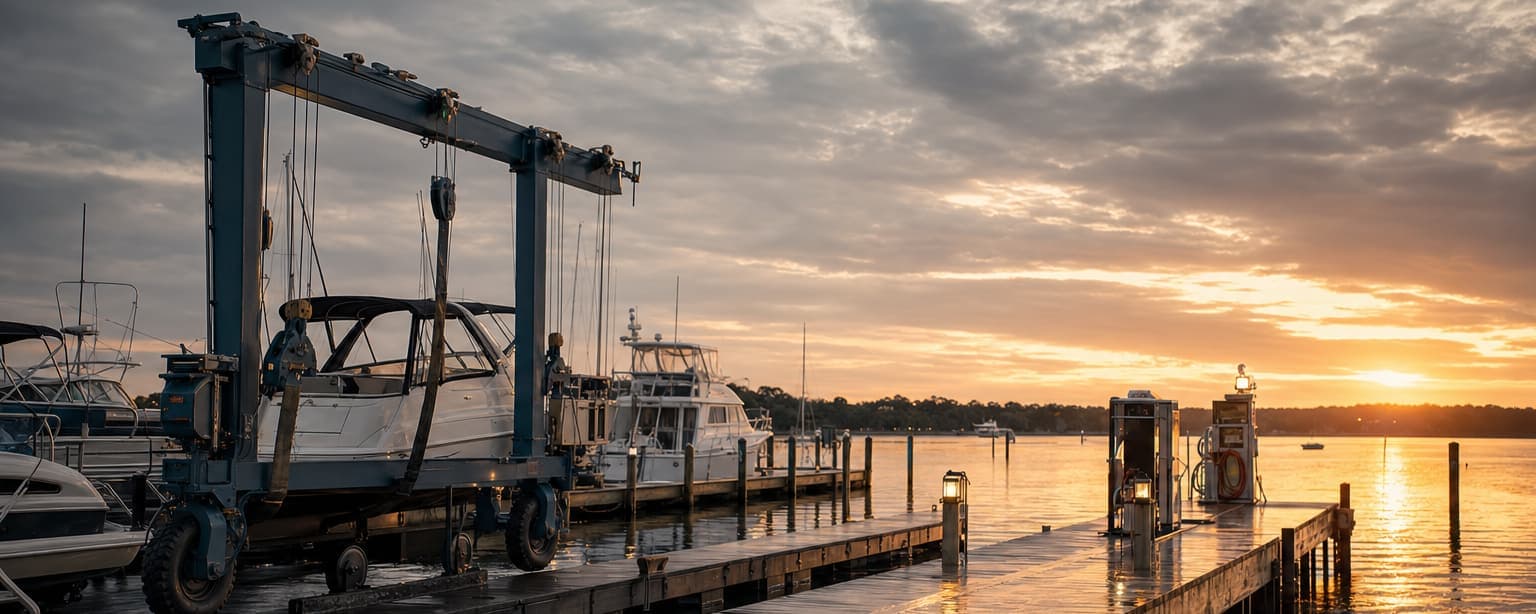
You are holding several hundred boats you do not own, on a property that floods by design.
Marinas, boatyards and boat dealers hold customers’ vessels in their care. We cover those, the docks and piers, fuel and pollution, and the named-storm exposure that defines the coast.
Tell us the situation.
One licensed human replies the same business day — not five agents, not an auto-responder. If the policy you have is already the right one, we will tell you.
We use this to quote and service your insurance, and we do not sell it or pass it to lead networks. Privacy policy.
Send us what you have. We’ll tell you if it’s right.
Your current policy paperwork, a renewal notice, or nothing at all. A licensed agent reads it and replies the same business day.
What marina businesses actually need.
General liability
The docks, the parking, the fuel dock and the yard, and injury to boaters, guests and contractors on your property.
Without it — Piers, ramps and wet surfaces with the public on them, before anyone touches a vessel.
Marina operators legal liability
Damage to customers’ boats in your care for storage, mooring or repair.
Without it — The boats are the value on site and none of them are yours.
Piers, docks and wharves
The structures themselves, which most property forms treat as a special class.
Without it — Docks are frequently excluded or heavily sublimited on a standard form.
Protection and indemnity
Marine liability, including injury to workers covered by maritime law.
Without it — Land-based workers comp does not answer a Longshore or Jones Act claim.
Pollution and fuel
Fuel spill, clean-up and third-party damage.
Without it — Pollution is excluded from property and liability, and fuel docks spill.
Named storm and windstorm
Hurricane and wind coverage for the site and the vessels in it.
Without it — The single event that damages everything on the property at once.
Crime and social engineering
Parts, outboards and fuel walking off the yard, and a deposit wired to somebody posing as a broker.
Without it — Wiring a deposit to somebody posing as a broker is not burglary, so property coverage stays shut. Ask for social engineering by name.
Group health and benefits
Dockhands and yard techs who can move a customer’s boat without touching anything.
Without it — Boat handling is learned on your dock, not at a school. Losing an experienced hand costs you damaged hulls before it costs you anything else.
What our marina clients ask us.
Are customers’ boats covered by our property policy?
No. Your property policy covers what you own, and the boats do not qualify. Marina operators legal liability is the coverage for vessels in your care, custody and control, and it is where the real exposure sits: a boatyard can be holding tens of millions of dollars of other people’s property with its own buildings worth a fraction of that. Set the limit against your peak on-site value, which for most yards is winter storage rather than the summer season.
What is the workers compensation complication?
That maritime employment is governed by federal law rather than state comp. Employees working on or adjacent to navigable water can fall under the Longshore and Harbor Workers’ Compensation Act, and crew members under the Jones Act — both of which a standard state workers comp policy does not answer without specific endorsement. Yards routinely discover this at the first serious injury. Describe exactly what your staff do and where they stand while doing it.
How is hurricane exposure handled?
With a named storm deductible, usually as a percentage, and with conditions you must actually meet. Many coastal marina policies require a written hurricane preparedness plan — hauling vessels, doubling lines, removing canvas — and can reduce or deny a claim where the plan was not executed. The plan is a policy condition rather than advice, so it needs to be written, staffed and rehearsed before the season.
Commercial insurance is 96% of what we do — it is not a department here, it is the whole business. Not ready to talk? The guides answer the questions this page raises in more depth. Already insured with us and need a certificate or a policy change? Ask the service team rather than starting a quote — it is faster and it goes to the people whose job it is. We also write home and auto, which is usually cheaper alongside the business policy than apart from it.
Handed a lease, a vendor packet or a client contract with insurance requirements? Paste it into the COI Requirements Decoder to see what each one means for your business, or read what the requirements mean.