
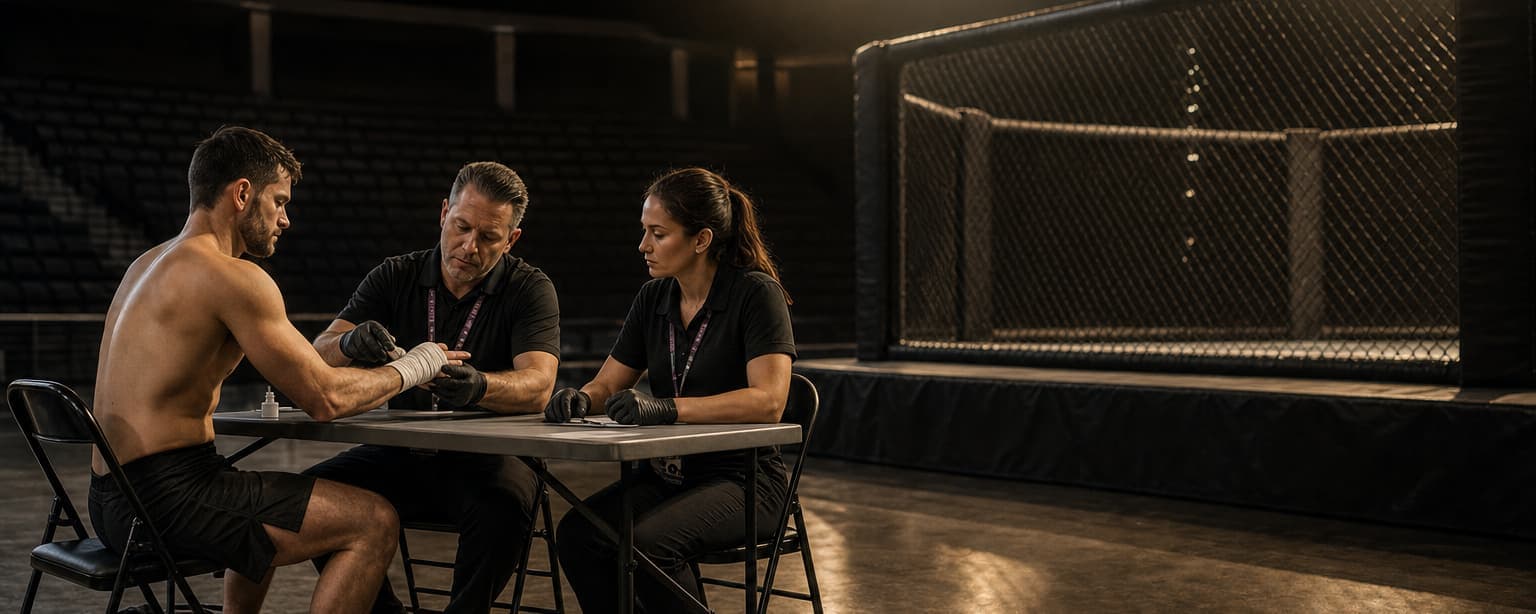
What insurance does an amateur MMA or boxing card actually need?
Whatever the state athletic commission says, and that is three things in most states: a medical policy paying a stated minimum for each contestant’s injuries, a death benefit, and a promoter’s bond; plus the general liability the venue will demand, which the commission does not set. The minimums range from no dollar figure at all in California to $1,000,000 for a brain injury in New York.
Tell us the situation.
One licensed human replies the same business day — not five agents, not an auto-responder. If the policy you have is already the right one, we will tell you.
We use this to quote and service your insurance, and we do not sell it or pass it to lead networks. Privacy policy.
Joe Gorman
Co-Founder | President of Commercial Lines
Fought amateur MMA and came close to turning pro, winning the bout in which he broke his jaw. He knows what a gym’s product actually is and why running a fight team changes the price. When a carrier that has never seen a mat starts asking its questions, he already has the answers. This agent will literally go to the mat for you.
Send us what you have. We’ll tell you if it’s right.
Your current policy paperwork, a renewal notice, or nothing at all. A licensed agent reads it and replies the same business day.
The detail
Federal law requires that no professional boxing match take place without supervision by a state boxing commission, and that the promoter provide “health insurance for each boxer to provide medical coverage for any injuries sustained in the match”, a physician at ringside and an ambulance on site.
California gives its athletic commission “sole direction, management, control of, and jurisdiction over all professional and amateur boxing” and “all forms and combinations of forms of full contact martial arts contests, including mixed martial arts”.
California sets no dollar minimum. A promoter “shall maintain a short-term medical assistance insurance program, approved by the commission” and “shall be responsible for paying any deductible amounts”; amateur sanctioning bodies must have “a medical insurance program satisfactory to the commission” covering all contestants. The promoter bond is $50,000.
Cal. Code Regs. tit. 4, § 290; Cal. Bus. & Prof. Code § 18646; 4 CCR § 216
Nevada requires medical coverage of $50,000 per licensed contestant and $25,000 per unlicensed amateur, with no deductible charged to the contestant.
Texas requires $50,000 for injuries and $100,000 for death per contestant, with the premium and any deductible paid by the promoter rather than from the purse, and a certificate filed at least ten days before the event; amateur combative-sports associations carry the same limits plus a $15,000 bond.
Connecticut requires $20,000 of medical, dental, surgical and hospital coverage and $50,000 for death, per match, and places amateur and professional boxing and mixed martial arts under the Commissioner of Emergency Services and Public Protection rather than a separate athletic commission.
Massachusetts requires not less than $10,000 of medical coverage and $100,000 for death for each contestant.
New York requires $50,000 for injury, $50,000 for death, and $1,000,000 for a life-threatening brain injury, per contestant.
The Association of Boxing Commissions’ amateur MMA rules leave the point to the state: “Insurance requirements will be determined at the discretion of the sanctioning Commissions.”
Association of Boxing Commissions, Unified Rules for Amateur MMA
In a study of UFC bouts, 31.9% ended in a knockout or technical knockout from head strikes, at 6.4 knockouts and 9.5 strike-related TKOs per 100 athlete-exposures; the meta-analysis across MMA competition puts the injury rate at 228.7 per 1,000 athlete-exposures with the head the most common site.
Hutchison et al., Am J Sports Med 2014; Lystad et al., Orthop J Sports Med 2014
What this means for you
- Start with the commission, not the sanctioning body. A sanctioning body writes the rules of the bout and often brings an accident policy with it. The state commission licenses the show and decides whether that policy is enough, and in California it approves the program outright. A promoter who has satisfied the sanctioning body has not yet satisfied anyone with the power to cancel the card.
- The contestant medical policy is not your liability policy. It pays the fighter’s bills, at the state minimum or above, whether or not anyone was at fault. It does nothing for the spectator who fell on the bleachers, the venue’s floor, or the lawsuit that follows a serious injury. That is promoter general liability, and the venue will ask for its certificate, usually naming the venue as additional insured.
- Read the participant exclusion on the liability policy. The Toughman case is the warning. A general liability policy with the athletic-participants exclusion attached gave the promoter no defense when a contestant died, because every negligence claim traced back to an excluded injury. Event liability for a card has to be written by a market that covers participants on purpose.
- The minimum is a floor, and the minimums are low. Massachusetts’ $10,000 does not pay for a night in intensive care. A promoter who cares about the fighters, or about the exposure when the minimum runs out, buys above it, and the difference in cost between $10,000 and $50,000 per contestant is small next to the venue and the officials.
- A gym that promotes is now two businesses. The gym policy was written for training at the gym. The card is an event, at a venue, with paid admission, licensed officials and a bond, and the commission will want to see policies written for that. A gym with a fight team and an annual smoker needs both sets of paperwork, and needs to know which one answers for which night.
Go deeper on any of these
Related questions
- Do amateur cards need the same insurance as professional ones?
In most states the commission regulates amateur MMA directly and sets a minimum, though sometimes a lower one: Nevada’s is $25,000 for an unlicensed amateur against $50,000 for a licensed contestant, and Texas applies the same $50,000 and $100,000 to amateur associations. California delegates amateur cards to approved sanctioning bodies, each of which must carry a medical program the commission accepts. Amateur boxing is the exception, because USA Boxing sanctions the show and its member policy answers for the bouts. Check the commission, because the answer is different in every state and changes.
- What the USA Boxing policy does and does not cover
- What does the venue want from a promoter?
A general liability certificate, usually $1,000,000 per occurrence and $2,000,000 aggregate, naming the venue and often its landlord as additional insureds, sometimes with liquor liability if there is a bar, and occasionally a waiver of subrogation. None of that is set by the commission, and none of it is in the contestant medical policy.
- Event promoter insurance
- Our gym is putting on its first smoker. Where do we start?
With the state commission’s website and a call to us. The commission page lists the promoter license, the bond, the medical minimums and the filing deadlines; we place the contestant medical policy and the event liability, and we will tell you where the gym policy stops.
- MMA gym insurance
Need this handled?
Reading about it and having it handled are different jobs, and the second one is ours. We place the accounts other brokers decline — claims history, a cancellation, an unusual operation, a business nobody wants to underwrite twice — and we will tell you when the policy you already have is the right one. Tell us the situation and a licensed human replies the same business day.
Written by the licensed brokers at Boring Insurance. Last updated 2026-09-06. See all guides.